The short answer
Business loans in NZ come in two main forms: unsecured loans assessed on your trading, and secured loans backed by property or assets. LoansOne arranges unsecured business loans and fast 1st or 2nd mortgages from $20,000 to $500,000 through non-bank lenders, with next-day funding possible and no credit file mark when you enquire.
What business loans are available in New Zealand?
Every business loan in New Zealand comes down to two questions: what is the lender relying on to get repaid, and how quickly do you need the money? Some loans lean on your trading income. Some lean on property. Some lean on the asset you’re buying. Work out which camp you’re in and the choice gets a lot simpler.
Banks still lend to Kiwi businesses, but their process suits owners with tidy financials, plenty of time and a long trading record. If you need money this week, your accounts are a year behind, or your credit file has a few marks on it, the non-bank and private lending market is usually where the answer sits. That’s the market LoansOne works in every day.
This page walks through every type of business finance available in NZ, explains what each one is built for and links to a detailed page on each. If you’d rather skip the reading, apply in about 30 seconds and an expert will tell you which option fits.
Which business loans don’t need property security?
These loans are assessed mainly on how your business trades. No house or commercial building goes on the line, which suits owners who lease their premises, who don’t want the family home involved, or who simply want a quick, clean deal.
- Unsecured business loans: $20,000 to $500,000 with no real estate security required in most cases. The broadest option, used for growth, stock, fit-outs, equipment deposits or a tax bill.
- Cash flow loans: sized from your bank statements and turnover, built to close the gap between paying out and getting paid.
- Short-term business loans: terms measured in months rather than years, for a job or opportunity that pays for itself quickly.
- Fast business loans: when the deadline matters as much as the amount. Next-day funding is possible when the paperwork is ready.
- Small business loans: the everyday SME borrowing guide, from a top-up of $20,000 to a six-figure expansion.
- Working capital loans: wages, stock, supplier terms and seasonal dips.
- Business line of credit: draw, repay and redraw as needed, so you only pay for what you use.
- Business overdraft alternatives: for when the bank has cut, capped or declined your overdraft.
- Merchant cash advance: an advance repaid from a share of your card and EFTPOS takings.
- Low doc business loans: when your financial statements are behind and you need a lender who will work from bank statements, GST returns or equity instead.
- Startup business loans: realistic options for new businesses with little or no trading history.
- Sole trader loans: for the self-employed, contractors and owner-operators.
- Bad credit business loans: defaults, arrears and past insolvency don’t automatically rule you out.
Which business loans are secured by property?
When there’s equity in property, lenders can move faster and lend more with far fewer questions about your financials. LoansOne arranges fast and flexible 1st and 2nd mortgages for business purposes from $20,000 to $500,000, with no cash flow or financial records needed and bad credit OK.
- Second mortgages: borrow against the equity in your home or commercial property while your bank’s first mortgage stays exactly where it is.
- First mortgages: a fast private 1st mortgage when the bank is too slow, says no, or the property is mortgage-free.
- Business loans against your house: how to turn residential equity into business funding, and whether a 1st or 2nd mortgage suits.
- Caveat loans: very short-term funding secured by a caveat registered on the property’s title with LINZ.
- Business bridging loans: cover the gap while a property sale settles or a large payment lands.
- Commercial property loans: buying or refinancing a commercial building, often using other property as extra security.
- Private business loans: why non-bank private lenders say yes when banks don’t, and how they weigh risk.
What about asset, equipment and vehicle finance?
Here the thing you’re buying becomes the security, registered on the PPSR (Personal Property Securities Register).
- Asset finance: the umbrella term, including hire purchase for business assets.
- Equipment and vehicle finance: utes, vans, trucks, fleets, IT gear and workshop equipment, for business use.
- Heavy equipment finance: diggers, tractors, loaders and plant, new or used, from a dealer or a private sale.
How can I free up cash tied in invoices or stock?
- Invoice finance: unlock cash sitting in unpaid customer invoices instead of waiting 30, 60 or 90 days.
- Trade finance: pay overseas suppliers and importers before your stock sells.
Can I get a loan to pay IRD?
Yes. Tax arrears grow quickly once IRD late payment penalties and use-of-money interest start adding up, and a loan can clear the debt in one hit.
- IRD debt loans: pay off income tax arrears and compare a loan with an IRD instalment arrangement.
- GST debt loans: clear GST and PAYE arrears specifically.
- Provisional tax funding: fund provisional tax instalments and see where tax pooling fits.
What finance is there for buying or restructuring a business?
- Business acquisition finance: buy a business or buy out a partner.
- Franchise loans: fund a franchise purchase or fit-out.
- Business debt consolidation: roll several expensive short-term debts into one repayment.
What does a business loan look like at different amounts?
Not sure what a particular figure looks like in practice? These pages lay out the realistic options at each level:
How do I choose the right business loan in NZ?
Start with your situation, not the product name. This table covers the most common reasons Kiwi business owners borrow.
| Your situation | Usually the best fit | Why |
|---|---|---|
| Steady trading, no property to offer | Unsecured business loan | Approved on your trading, no real estate security in most cases |
| Customers pay slowly, bills don’t wait | Cash flow loan or invoice finance | Sized on bank statements or your debtor book |
| You own property with equity, bank is slow or said no | Second mortgage | Fast, and your bank’s first mortgage stays in place |
| Property owned outright, or you want out of the bank | Private first mortgage | First ranking on title, flexible structure |
| Financials behind or credit has marks | 1st or 2nd mortgage | No cash flow or financial records needed, bad credit OK |
| Buying a ute, truck or machine | Equipment or asset finance | The asset is the security |
| IRD or GST arrears | Tax debt loan | Clears the debt and stops penalties growing |
| Waiting on a sale or settlement date | Bridging or caveat loan | Short term, repaid when the money lands |
Two rules of thumb help most owners:
- Match the term to the purpose. Don’t fund a five-year asset with a three-month loan, or a three-week gap with a five-year one.
- Use security when it helps you, not by default. Property security can unlock a bigger amount, a faster yes and a sharper price. But if trading is strong, an unsecured loan keeps your property free.
For a deeper side-by-side, read secured vs unsecured business loans or our unsecured loan vs second mortgage comparison. The loan matcher gives you a quick steer in under a minute.
Should I go to my bank or a private lender first?
If you have time, clean financials and a strong credit file, it’s worth asking your bank. Bank money suits long-term, low-risk borrowing, and nobody should pretend otherwise.
But banks are built for the typical case. They tend to stall when:
- you need funds in days rather than weeks
- your latest accounts aren’t finished, or show a tough year
- there’s a default, arrears or an IRD debt on the record
- the property is unusual, such as a lifestyle block or mixed-use building
- the request falls outside their standard business lending appetite
Private lenders exist for exactly those situations. They read the whole story, lean on security or bank statements instead of a full set of accounts, and decide quickly. Many owners use private finance as a bridge: get the job done now, then refinance to the bank once the accounts catch up. Our bank vs private lender comparison goes into the trade-offs in detail.
What does LoansOne arrange?
LoansOne focuses on the two products that solve most problems for New Zealand business owners:
- Unsecured business loans from $20,000 to $500,000. No real estate security required in most cases.
- Fast and flexible 1st or 2nd mortgages from $20,000 to $500,000, for business purposes. No cash flow or financial records needed. Bad credit OK.
An expert reviews every application on your individual circumstances, then matches you to the lender most likely to say yes on the best terms for that situation. Your details aren’t sprayed across dozens of lenders. One well-matched application beats ten speculative ones, for your credit file and for the speed of the answer.
Starting an enquiry is free, takes about 30 seconds online and doesn’t mark your credit file.
What do lenders look at for a business loan?
It depends on the product, but most non-bank lenders weigh up some mix of:
- Trading history: how long the business has operated and how steady its deposits are.
- Bank statements: recent months of business account activity, especially for unsecured and cash flow loans.
- Security: the equity in any property offered, checked against the record of title.
- Credit history: read for context, not as an automatic pass or fail.
- Purpose and exit: what the money is for and how it gets repaid.
The loan readiness check is a good way to prepare, and the business loan calculator lets you test repayments before you apply.
How much does a business loan cost?
There’s no honest single answer, which is why we don’t publish rates. Pricing depends on the loan type, whether there’s security, the loan-to-value ratio, the term, your trading strength, your credit history and how fast you need the funds. A second mortgage on a Remuera home with plenty of equity prices very differently from an unsecured loan to a six-month-old business.
Every LoansOne loan is priced on your circumstances, and the team works to get you the sharpest rate available for your situation. When you have offers in hand, the compare loan offers tool helps you look past the headline figure to the total cost.
How fast can I get a business loan?
Faster than most owners expect. Once an expert has reviewed your application, a lender contacts you directly. With documents ready and a clear purpose, next-day funding is possible and many clients are paid out within 24 hours. Property-secured deals add a valuation and title work, but private lenders move on these far faster than banks.
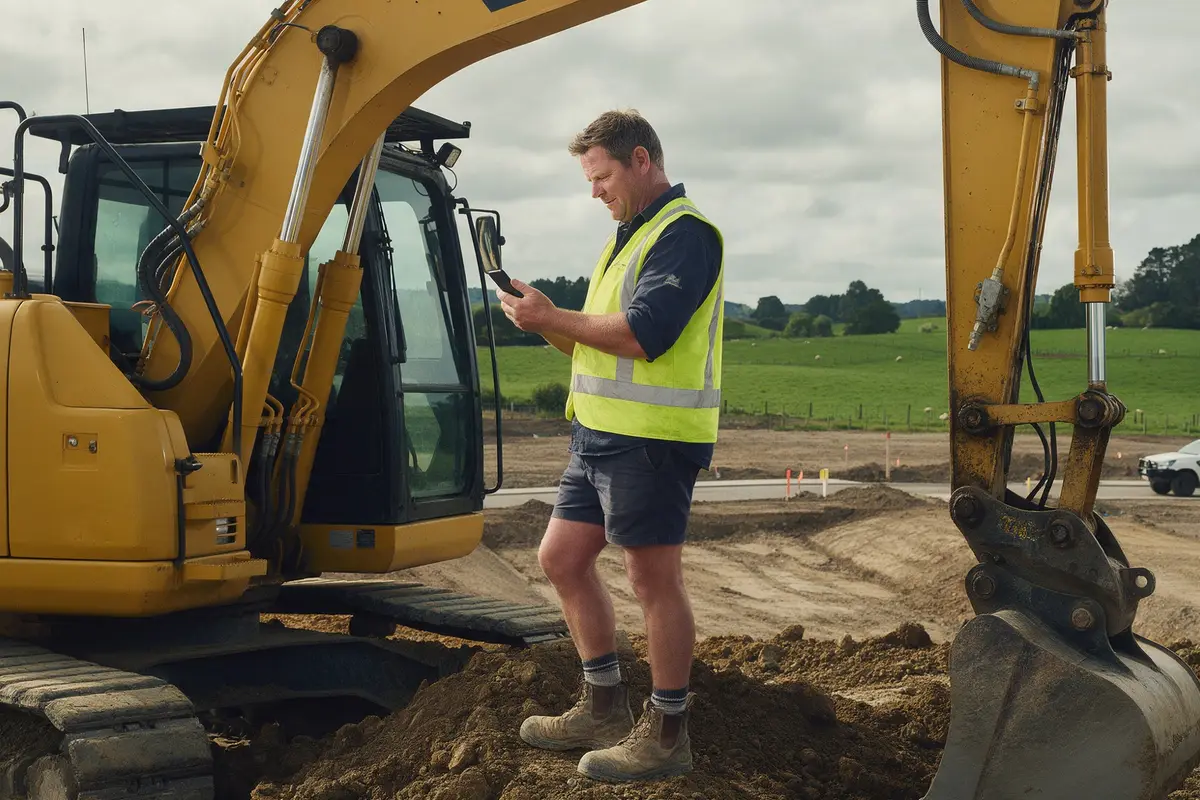
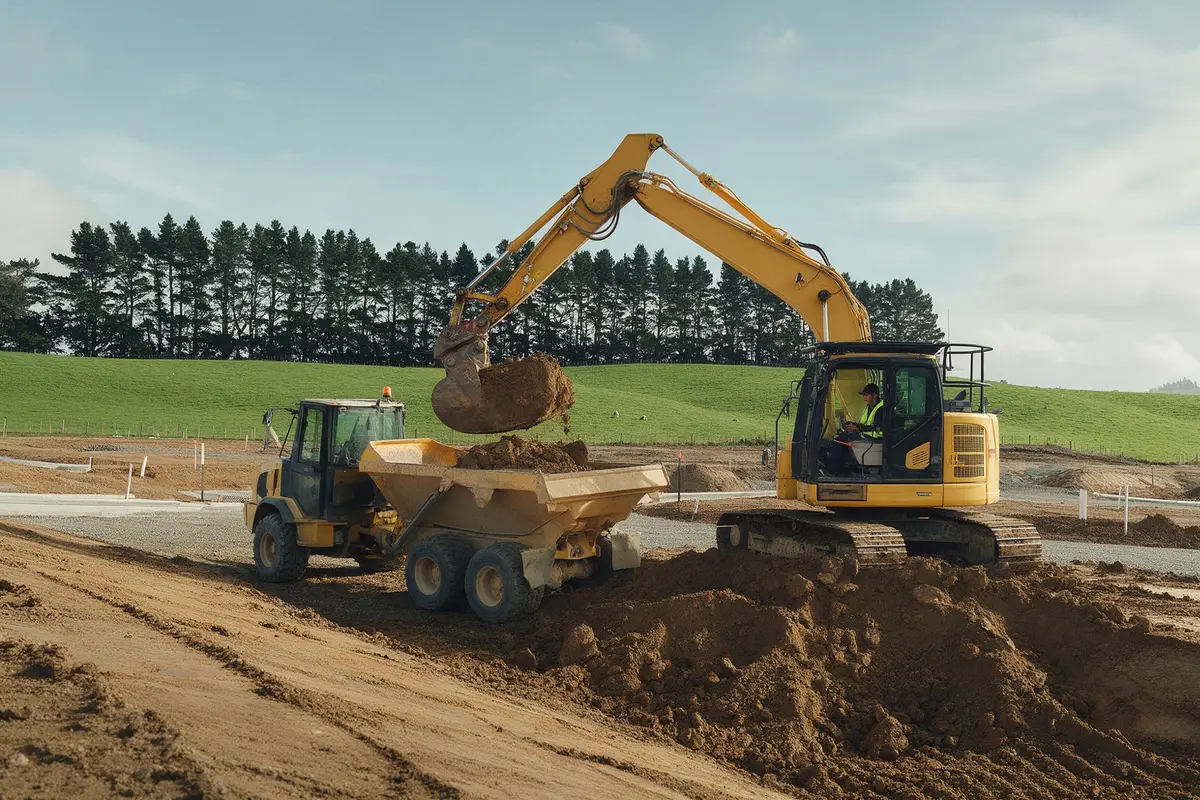
Here’s how that plays out. Picture a Hamilton earthmoving contractor who wins a subdivision contract but needs a second excavator on site within a fortnight. The bank wants two years of accounts and several weeks to decide. Option one is equipment finance on the machine itself. Option two is a second mortgage over the contractor’s yard, which leaves the bank’s mortgage untouched and gets money into the account within days. LoansOne’s job is to lay those options out side by side and match the contractor to the lender that fits.
Next step
Tell us how much you need and what it’s for. Apply online in about 30 seconds, free and with no mark on your credit file, or call 09-888 5252 to talk it through with the team at 48 Shortland Street, Auckland. We work with business owners right across New Zealand.