The short answer
Business debt consolidation replaces several business debts, such as short-term loans, merchant cash advances, overdue supplier accounts or IRD arrears, with one new loan and one repayment. It works when the new loan costs less overall or frees up cash flow. LoansOne arranges unsecured loans and 1st or 2nd mortgages from $20,000 to $500,000.
How does business debt consolidation work?
The idea is simple. You take out one new loan, use it to pay off several existing debts, and from then on you make one repayment to one lender. Instead of four or five deductions hitting your account on different days, you have one, on a schedule you know.
It is most useful when a business has picked up a stack of short-term debts during a tough patch. A cash advance here, a quick unsecured loan there, a supplier account that has drifted past terms, and a GST bill sitting with Inland Revenue. Each one made sense at the time. Together they can drain cash flow, especially when some take repayments daily or weekly.
LoansOne arranges consolidation through:
- Unsecured business loans from $20,000 to $500,000, with no real estate security required in most cases
- Fast and flexible 1st or 2nd mortgages from $20,000 to $500,000 for business purposes, with no cash flow or financial records needed and bad credit OK
What debts can you consolidate?
Most business debts can be rolled in. The usual candidates:
- Merchant cash advances taken from card takings each day. See our guide to merchant cash advances for why they can pinch.
- Short-term business loans with weekly or daily repayments
- Business credit cards used to cover gaps
- Overdue supplier accounts where trade terms are at risk
- IRD arrears such as GST, PAYE or income tax. Clearing these stops penalties and interest building. See IRD debt loans.
- Equipment or vehicle finance that is nearly paid off but still taking a big monthly bite
Debts secured over assets you want to keep, such as a ute on finance, may be better left alone if the terms are reasonable. Consolidation is about fixing what is expensive or awkward, not moving everything for the sake of it.
When does consolidating business debt make sense?
It is worth a look if one or more of these sound familiar:
- Repayments come out daily or weekly and you never get a clear run at your cash flow.
- You are paying several lenders, each with fees and different dates.
- Some debts are expensive relative to what you could borrow now, especially if you can offer property security.
- IRD is part of the picture, and penalties and interest are adding up.
- You keep borrowing to make repayments, which is a sign the structure has stopped working.
It is less likely to help if the business is losing money every month. Consolidation fixes the shape of your debt, not a business that is not covering its costs. In that case, the first job is the trading problem.
Does it actually save money? How to check
This is the question that matters, and it is easy to get wrong. A lower repayment feels like a win, but stretching debt over a much longer term can mean paying more overall. Check both sides:
| What to compare | Your existing debts | The consolidation loan |
|---|---|---|
| Total still to repay | Add up every remaining payment, including fees | All repayments plus establishment and other fees |
| Repayment frequency | Daily, weekly, monthly? | Usually one regular repayment |
| Time to clear | When does each debt end? | One end date |
| Early repayment | Any break costs or fixed fees? | Can you repay early, and on what terms? |
| Security | Unsecured, or over specific assets? | Unsecured, or over property |
| Cash flow freed up | Current total monthly outgoing | New monthly outgoing |
Plug your figures into the compare loan offers tool to see total cost side by side, and use the business loan calculator to test different terms. Every LoansOne loan is priced on your individual circumstances, and the team works to get the sharpest rate available for your situation. That means looking at what drives price for you: security, credit history, trading record, loan size and term.
A useful rule: if you can afford it, choose the shortest term that still gives your cash flow room. Our comparison of short-term vs long-term business loans explains the trade-off.
Secured or unsecured consolidation?
| Unsecured consolidation loan | Second mortgage consolidation | |
|---|---|---|
| Security | None in most cases | Property, behind your bank’s 1st mortgage |
| Amounts | $20,000 to $500,000 | $20,000 to $500,000 |
| How it is assessed | Mainly business bank statements and trading | Mainly the property; no cash flow or financial records needed |
| Credit history | Cleaner files fare better | Bad credit OK |
| Best for | Smaller stacks of debt, strong trading | Larger or expensive debts, patchy credit, owners with equity |
If you own property, a second mortgage leaves your bank loan untouched while clearing everything else. Check how much equity you have with the equity calculator. If you would rather not use property, our comparison of unsecured loans vs second mortgages sets out the differences.
Two scenarios
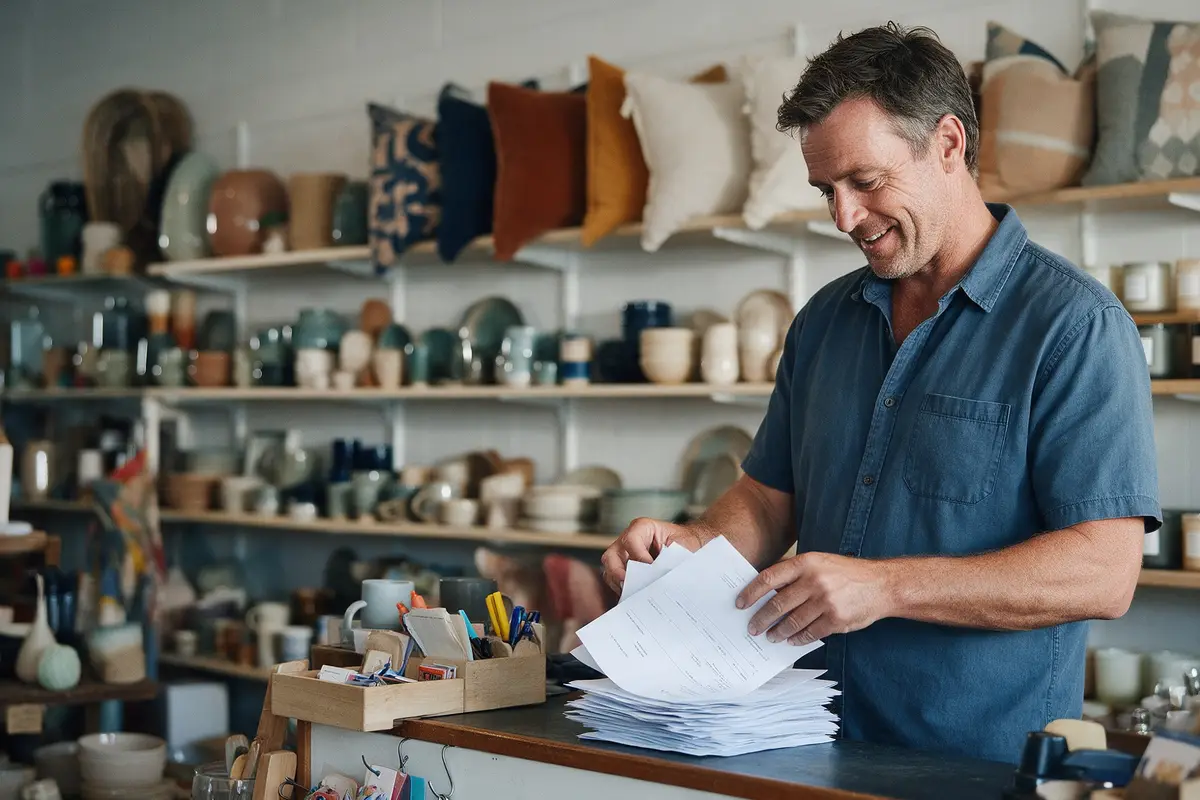
A Whangārei homewares retailer. After a slow winter and a big pre-Christmas stock order, the owner had two merchant cash advances taking a slice of every card sale, a short-term loan with weekly repayments and a GST period in arrears. Daily takings were healthy but the shop never seemed to have cash. An unsecured consolidation loan paid off all four, and the business moved to one monthly repayment. With card takings no longer split, buying stock for the next season became straightforward again.
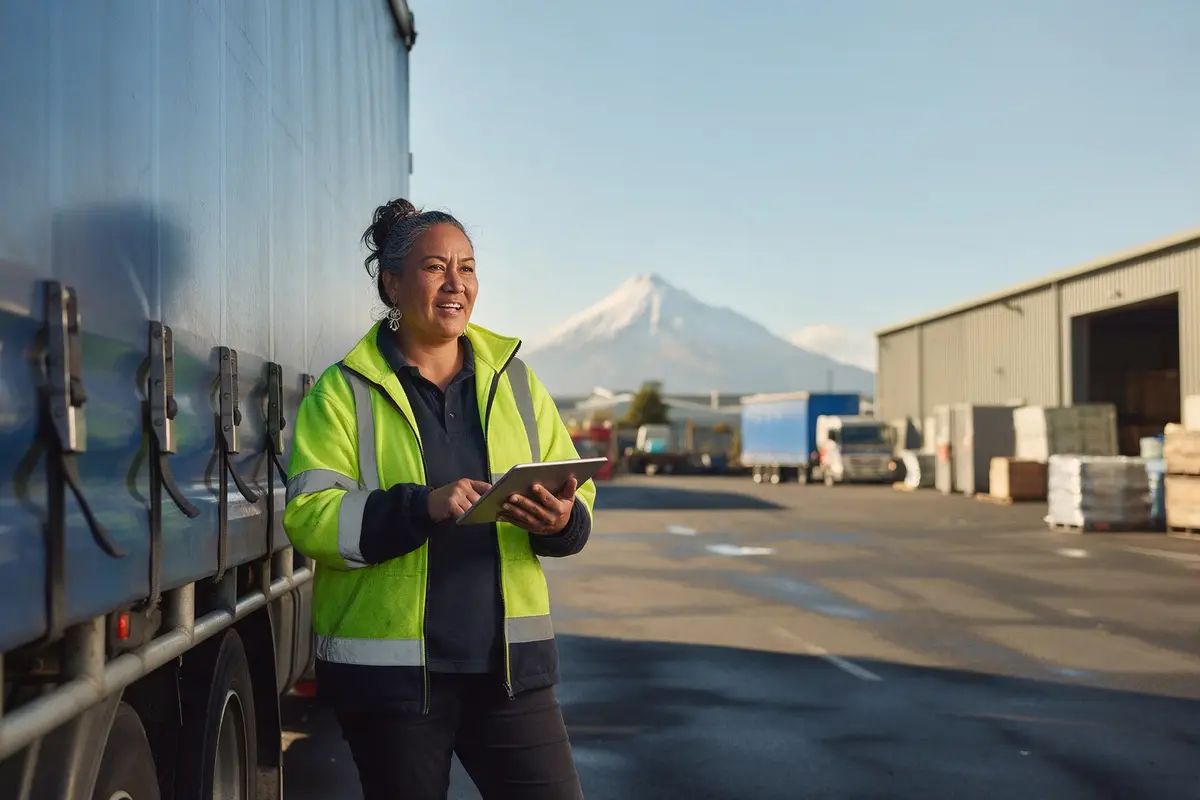
A New Plymouth transport operator. A trucking business had a costly short-term loan from a breakdown repair, a business credit card carrying fuel costs, and overdue PAYE. The owner had equity in a rental property. A second mortgage cleared all three, including the PAYE, which stopped the monthly non-payment penalties straight away. For more on funding in this sector, see transport business finance.
These are illustrative scenarios, not real clients.
What lenders look at for a consolidation loan
Lenders want to see that consolidation will actually leave the business in a stronger position. Expect them to check:
- The full list of debts. Every balance, repayment and payout figure, so nothing is missed.
- Why the debts built up. A one-off event, such as a lost contract, a slow season or a large repair, reads very differently from ongoing losses.
- Current trading. Recent bank statements showing deposits that comfortably cover the new single repayment.
- Tax position. Whether GST and PAYE are filed. If IRD is owed, the loan can clear it, but lenders need the real figure from myIR.
- Security. Property equity opens up larger amounts and is the main path where credit has taken a hit.
Mistakes to avoid when consolidating
Leaving a debt out. If one cash advance or card is left running, the daily deductions continue and the benefit shrinks. Consolidate everything that is costly or awkward.
Re-borrowing straight away. Once the old facilities are paid off, close them where you can. Running them back up is the fastest way to end up worse off than before.
Stretching the term too far. A very long term lowers the repayment but raises total cost. Pick the shortest term your cash flow can comfortably carry.
Ignoring the cause. If the debts came from thin margins or slow-paying customers, fix that too. A working capital loan or invoice finance may suit the underlying gap better than more term debt.
How to apply for a consolidation loan
- List every debt. Lender, balance, repayment, frequency, end date and any early repayment cost.
- Get payout figures. Ask each lender for a written payout amount.
- Pull your bank statements. Three to six months for the business account.
- Check your IRD position in myIR if tax is involved.
- Apply. Start online in about 30 seconds. It is free and does not mark your credit file.
An expert reviews your file and matches you to the right lender. Your details are not sprayed to dozens of lenders. Next-day funding is possible, and lenders can often pay existing creditors directly at settlement so nothing slips through.
Next step
If repayments are coming from every direction, one well-structured loan can give your business room to breathe. Apply now or call 09-888 5252 and talk through your debts with the team.