The short answer
A short term business loan in New Zealand is finance repaid over months rather than years, usually somewhere between three and 24 months. It suits a one-off need with a clear payback, such as stock, a tax bill or a contract on long payment terms. LoansOne arranges unsecured and property-secured options from $20,000 to $500,000.
What is a short term business loan?
A short term business loan is finance you repay over months rather than years. In New Zealand the term usually sits somewhere between a few months and two years, and the loan is built around a single job: a stock order, a tax bill, a contract that pays on 60-day terms, or a piece of gear that earns its keep quickly.
The logic is simple. You borrow for the life of the need, not longer. When the need is finished, so is the debt, and you go into the next season with a clean slate instead of a repayment that outlives the reason you took it on.
LoansOne arranges two broad types of short term business finance:
- Unsecured business loans from $20,000 to $500,000, assessed mainly on how your business trades. No real estate security is required in most cases.
- Property-secured loans, a fast and flexible 1st or 2nd mortgage for business purposes from $20,000 to $500,000. No cash flow or financial records are needed and bad credit is OK, because the property does the heavy lifting.
When does a short term loan beat a long one?
Match the term to how long the money takes to come back. That one rule sorts out most decisions, and it is the core idea behind our short term vs long term comparison.
| What you are funding | How long until it pays back | Sensible term |
|---|---|---|
| Seasonal stock for Christmas or the ski season | 2 to 6 months | Short |
| Wages and materials on a job paid by progress claims | 1 to 6 months | Short |
| GST, PAYE or provisional tax arrears | 6 to 18 months of trading | Short |
| Deposit while a property sale settles | Weeks to a few months | Short (bridging) |
| A shop or clinic fit-out | Several years | Longer |
| Buying commercial premises | Many years | Long |
Short wins when:
- The payback is clear and close. A signed contract, a seasonal sales peak or a property sale gives the lender a visible exit.
- You want the lowest total cost. A higher annual rate over 6 months can cost less in total than a lower rate stretched over 5 years.
- You don’t want debt hanging over next year. Clearing the loan inside the same season keeps your balance sheet tidy for the next time you need to borrow.
- Your situation is about to improve. If your accounts are behind or you are mid-way through a turnaround, a short loan gets you through now and leaves room to refinance onto cheaper terms later.
Long wins when the thing you are buying lasts for years, or when keeping each repayment small matters more than the total interest bill. If that sounds like you, look at working capital loans or longer property-secured lending instead.
How much does a short term business loan cost?
We don’t publish rates, because no two loans are priced the same way. Every loan is priced on the client’s individual circumstances, and LoansOne works to get the sharpest rate available for that situation. What moves the price:
- Security. A loan backed by property is lower risk for a lender than an unsecured loan, so it is usually priced more keenly.
- Term and repayment style. Interest-only with a lump sum at the end prices differently from weekly principal and interest repayments.
- Trading strength. Steady deposits in your business bank account reassure an unsecured lender.
- Credit history. Defaults, arrears or a past insolvency don’t rule you out, but they shape which lenders fit.
- The exit. A confirmed source of repayment, like an unconditional sale, makes a short loan easier to price well.
Look past the headline rate. Establishment fees, line fees, early repayment terms and how interest is charged all change what you actually pay. Our business loan calculator helps you test repayments, and our compare loan offers tool lines up the total cost of two quotes side by side.
What do Kiwi businesses use short term finance for?
Short term loans work best when the need has a start and a finish. A few illustrative scenarios:
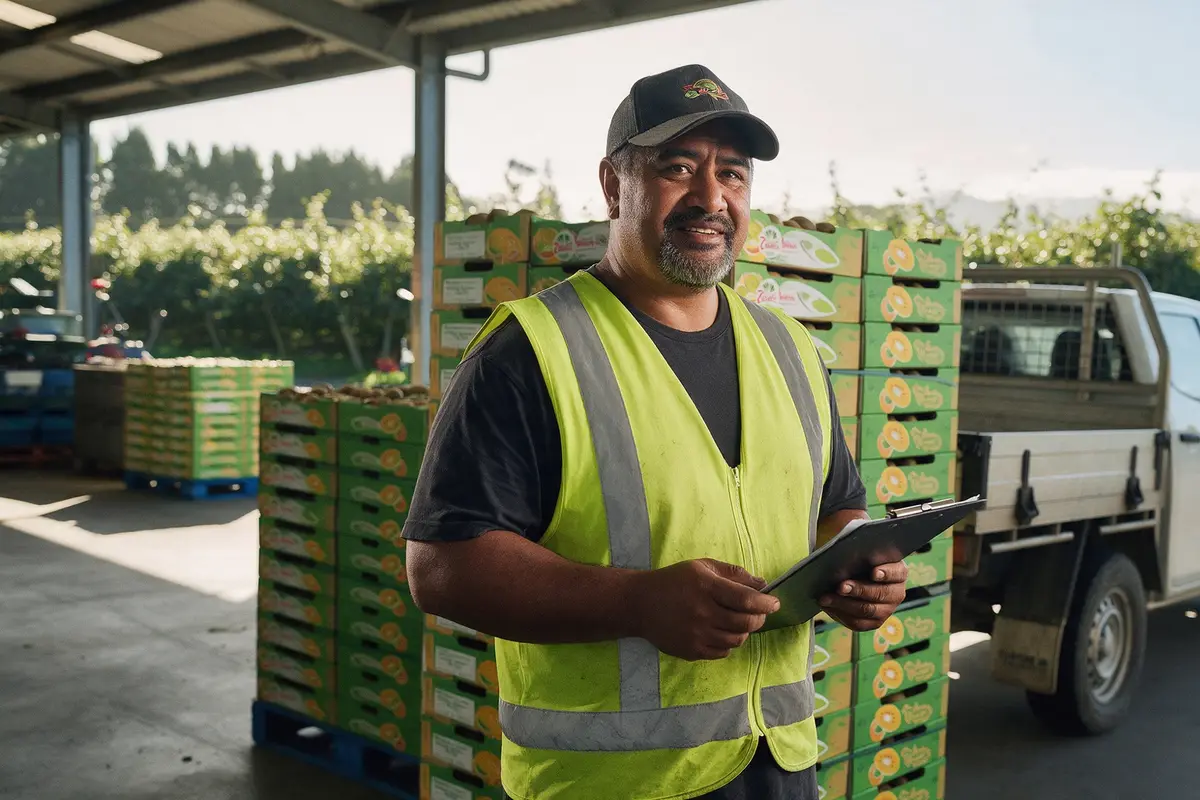
A Tauranga kiwifruit contractor gearing up for harvest. Picking crews, hire gear and fuel all need paying weeks before the packhouses pay out. A short unsecured loan covers the build-up and is cleared from harvest income.
A Nelson retailer buying for summer. Suppliers want payment before the tourists arrive. A loan of $60,000 over a few months funds the stock order and is repaid as the tills ring through January.
A Christchurch builder between progress payments. The frame is up, the materials bill is due and the next claim won’t be paid for another month. Short term finance keeps subbies paid and the job on schedule.
A Hamilton earthmoving operator with an IRD bill. GST and PAYE have fallen behind after a wet winter stalled work. A short loan clears the arrears in one go, stops penalties and interest building, and is repaid as summer jobs come in. Our IRD debt loans page explains that option in detail.
How do repayments work on a short term business loan?
There are three common structures, and the right one depends on where the repayment money is coming from.
- Regular repayments. Weekly, fortnightly or monthly instalments of principal and interest. This suits unsecured loans repaid from everyday trading income.
- Interest-only, then a lump sum. You service the interest during the term and repay the full amount at the end. This is common for property-secured loans where the exit is a sale, a refinance or a large payment.
- Lump sum with interest at the end. Some property-secured lenders allow interest to be paid on exit, which protects cash flow during the term. Not every lender offers this, and it changes the pricing.
Whatever the structure, have a clear exit before you sign. “Trading will pick up” is a hope. “Our contract pays $140,000 on completion in March” is an exit. If you want to see how big your gap is before you borrow, run your numbers through the cash flow gap calculator.
What do lenders need for a short term loan?
It depends on the type of security.
For an unsecured short term loan, expect a lender to ask for:
- Recent business bank statements
- Your NZBN or Companies Office details, and how long you have been trading
- Your IRD position, including any GST or PAYE arrears and whether an instalment arrangement is in place
- ID for the directors or owners
For a property-secured short term loan, the focus shifts to the property:
- The address and ownership of the property you are offering as security
- What is owed on it now and who holds the existing mortgage
- Your plan to repay at the end of the term
No cash flow or financial records are needed for property-secured lending, which is why it suits business owners whose accounts are a season or two behind. Not sure where you stand? The loan readiness check takes a couple of minutes.
Short term loan, overdraft or line of credit?
All three can fund short term needs, but they behave differently.
| Short term loan | Bank overdraft | Line of credit | |
|---|---|---|---|
| How you get the money | Lump sum, paid out once | Draw as needed on your account | Draw, repay and redraw up to a limit |
| Best for | One defined need with a clear payback | Small day-to-day swings | Recurring, unpredictable gaps |
| Typical security | Unsecured or property | Often property or a general security agreement | Varies |
| Risk | Fixed end date keeps you disciplined | Bank can reduce or pull the limit | Easy to let the balance sit high |
If your bank has cut or refused your overdraft, our page on business overdraft alternatives covers the options. If the gap is ongoing rather than one-off, a business line of credit may suit better than a fixed loan.
Why arrange your short term loan through LoansOne?
Short term finance only helps if it arrives in time and fits the job. That’s where the way we work matters.
- Fast decisions. An expert reviews every application, then a lender makes contact. Next-day funding is possible, and many loans are paid out within 24 hours.
- No credit file mark when you enquire. You can find out where you stand before committing to anything.
- Matched, not shopped around. We don’t spray your details across dozens of lenders. We match you to the lender that suits your purpose, security and timeframe.
- Secured and unsecured options. From $20,000 to $500,000, with bad credit considered.
Starting is free and takes about 30 seconds. You can apply online now and tell us what the money is for and when it will come back.
Next step
If you have a clear need and a clear payback, a short term business loan is often the cleanest way to bridge the two. Apply in about 30 seconds or call the team on 09-888 5252 to talk through your timing, your security and the term that fits.