The short answer
Yes, sole traders in NZ can get business loans. Lenders assess you personally, using your bank statements, IRD records and any security you can offer. LoansOne arranges unsecured loans from $20,000 to $500,000 and property-secured 1st or 2nd mortgages that need no financial records, with bad credit considered and no GST registration required.
Can a sole trader get a business loan in NZ?
Yes, and plenty do. Sole traders are the backbone of a lot of New Zealand industries: builders, sparkies, plumbers, hairdressers, contractors, consultants, cleaners, photographers and farm contractors.
The key difference from a company is simple. As a sole trader, there’s no separate legal entity. You are the business. You file a personal income tax return (an IR3) with Inland Revenue, the business income is your income and the business debts are your debts.
For lenders, that means they’re not assessing a business on paper. They’re assessing you, the way you earn and how you manage money. That can actually work in your favour, because you don’t need company accounts, director guarantees or a complicated structure to get a decision.
How do lenders assess a sole trader?
Lenders want to answer two questions: is your income steady enough to cover repayments, and what happens if it isn’t? To answer them, they’ll typically look at:
- Bank statements. The most important document for an unsecured loan. Regular deposits from clients show the business is real and trading.
- IRD records. Your IR3 returns and any statements showing your tax position. Being up to date with Inland Revenue is a big plus.
- GST returns, if you’re registered.
- Invoices and contracts, especially if you have a regular client or a big job lined up.
- Your credit history, although this matters less for property-secured lending.
- Security, such as equity in your home.
Many sole traders also receive schedular payments with tax already deducted. That’s fine. Lenders simply look at what lands in your account.
Can you get a business loan without GST registration?
This is a common worry, and the answer is yes. You must register for GST once your turnover is, or is expected to be, over $60,000 in a 12-month period. Below that, registration is optional, so many smaller sole traders aren’t registered at all.
Lenders don’t need GST returns to assess you. They can use your bank statements and IR3 income tax records instead. And if you’re borrowing against property, no cash flow or financial records are needed at all.
The only practical limit is size. Some unsecured lenders set a minimum turnover, so very small operations may find a property-secured loan a better fit than an unsecured one.
Which loan suits which kind of sole trader?
| Your situation | Option that usually fits | Why |
|---|---|---|
| Steady income through a business bank account | Unsecured business loan | Assessed on cash flow, no property needed in most cases |
| Own a home with equity, need money fast | 2nd mortgage behind your bank loan | No financial records needed, bad credit considered |
| Need a ute, van or tools | Equipment and vehicle finance | The vehicle or equipment is the security |
| Books are behind or income is irregular | Low doc business loan or property-secured loan | Lenders use other evidence instead of full financials |
| Owe Inland Revenue | IRD debt loan | Clear the debt and stop penalties and interest building |
Can sole traders with bad credit get a loan?
Bad credit is common among sole traders. One slow-paying client can turn into a missed payment of your own, and suddenly there’s a default on your file. It doesn’t mean you can’t borrow.
Your options depend mostly on whether you own property:
- With property: fast 1st and 2nd mortgages from $20,000 to $500,000 for business purposes consider bad credit, because the lender’s main security is the property.
- Without property: some unsecured lenders will look past older defaults if your recent bank statements are strong and the reason is explained. Fresh or repeated defaults make unsecured lending much harder.
Our bad credit business loans page covers this in more depth, including how lenders view defaults, arrears and past insolvency.
What do sole traders use business loans for?
Every sole trader’s needs are different, but these come up most often:
- A new or second vehicle. A ute, van or truck to take on more work.
- Tools and equipment. Upgrading gear so you can quote on bigger jobs.
- Covering slow payers. Bridging the gap when a client pays on long terms.
- Tax bills. Provisional or terminal tax landing at the same time as a quiet month.
- Taking on a bigger contract. Buying materials upfront before the progress payments arrive.
- Hiring your first employee. Covering wages for the first few months while revenue catches up.
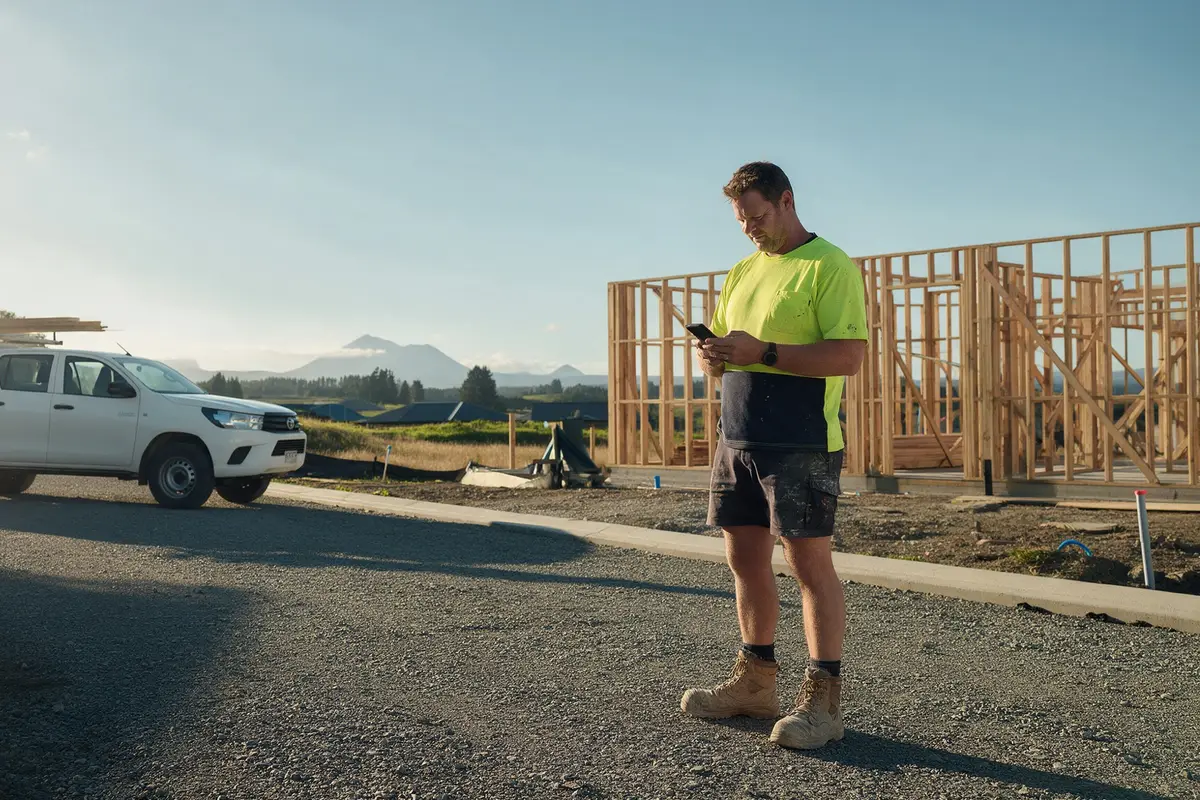
Illustrative example: a self-employed builder near Taupō is offered a run of new-build contracts but needs a second ute and a trailer to put an apprentice on the road. (Our business loans for builders page covers trade-specific funding.) Asset finance funds the ute, and a small unsecured loan covers the trailer, tools and the first weeks of wages.
Illustrative example: a Canterbury dairy contractor has strong income in spring and autumn but a lean winter. A $40,000 loan covers machinery servicing and wages through the quiet months, then gets paid down once the busy season starts.
Illustrative example: a self-employed hairdresser renting a chair in an Auckland suburb wants to open her own small salon. She isn’t GST registered yet and her income runs through a personal account. A second mortgage over her apartment funds the fit-out, with no financial records required.
Sole trader or company: does it change your finance?
Not as much as people expect. Lenders will lend to either. The main differences:
- A sole trader borrows personally. There’s no separate personal guarantee because you’re already personally responsible.
- A company borrows in its own name, but lenders almost always want the directors to guarantee the loan anyway.
- Company accounts can make larger unsecured loans easier, while sole traders rely more on bank statements and IRD records.
If you’re thinking about moving from sole trader to a company, talk to your accountant about the timing. Sometimes it’s easier to borrow before the change, while your trading history sits in one name.
How can a sole trader make their application stronger?
- Run business income through one dedicated account. It’s the clearest evidence you can give.
- Keep Inland Revenue up to date. Filed returns and an arrangement in place for any debt both help.
- Know your numbers. Roughly what comes in each month, what goes out and what you’re borrowing for.
- Be upfront about credit issues. A clear explanation beats a surprise.
- Apply once, properly. Multiple applications can leave multiple marks on your file.
Our loan readiness check helps you spot gaps before you apply.
How fast can a sole trader get funded?
Faster than most people expect, provided the paperwork is ready. The process is simple:
- Start online in about 30 seconds. It’s free and doesn’t mark your credit file.
- An expert reviews your situation. We look at what you need, what you own and how you earn, then work out which lender suits you.
- A lender makes contact. They confirm the details and ask for anything else they need.
- Funding. Next-day funding is possible, and many clients are paid out within 24 hours.
Property-secured loans are often the quickest, because there are no financial statements to wait on. For unsecured loans, having recent bank statements to hand is what speeds things up. If time is the main pressure, see our page on fast business loans.
How are sole trader loans priced?
Every loan is priced on your individual circumstances. The key drivers are whether the loan is secured or unsecured, the strength and consistency of your income, your credit history, the amount and the term. Secured loans usually price more sharply than unsecured ones. We match you with the right lender for your situation and work to get the sharpest rate available, rather than spraying your application across the market.
Next step
As a sole trader, your time is your income, so the application should be quick. Starting is free, takes about 30 seconds and doesn’t mark your credit file. Apply in about 30 seconds or call 09-888 5252 to talk to an expert about your situation.