The short answer
Small business loans in New Zealand are finance for SMEs to fund stock, equipment, wages, tax bills, fit-outs or growth. The right type depends on the purpose and your security. LoansOne arranges unsecured loans and 1st or 2nd mortgages for business purposes, each from $20,000 to $500,000, matched to a suitable non-bank lender.
What are small business loans used for in NZ?
New Zealand runs on small business. Cafés, tradies, retailers, contractors, clinics, online stores and family firms all need finance at some point, and very rarely for the same reason. That’s why the first question isn’t “how much can I borrow?” but “what is the money for?”
The most common uses for SME finance:
- Stock and inventory ahead of a busy season or a supplier deal
- Equipment and vehicles such as utes, vans, ovens, hoists or machinery
- Wages and supplier bills while waiting for customers to pay
- Tax bills including GST, PAYE and provisional tax
- Fit-outs and upgrades for a new site or a tired one
- Growth such as a second location, a new hire or a bigger contract
- Buying out a partner or buying another business
LoansOne arranges two main types of small business finance, both from $20,000 to $500,000: unsecured business loans, where no real estate security is required in most cases, and fast, flexible 1st or 2nd mortgages for business purposes, where no cash flow or financial records are needed and bad credit is OK.
Which type of small business loan fits your need?
Matching the loan type to the purpose saves money and hassle. Here’s a quick guide to the loans most Kiwi SMEs use.
| What you need | Loan type that usually fits | Learn more |
|---|---|---|
| A general lump sum, no property to offer | Unsecured business loan | Unsecured business loans |
| Cover wages, stock or supplier terms | Working capital loan | Working capital loans |
| A ute, van, truck or machine | Equipment or vehicle finance | Our equipment finance page |
| Cash tied up in unpaid invoices | Invoice finance | Our invoice finance page |
| A bigger amount, or bad credit, with property | 1st or 2nd mortgage | Second mortgages |
| Recurring, unpredictable gaps | Line of credit | Our line of credit page |
Not sure? Our loan matcher tool asks a few questions and points you at the right category. For a full overview of every option, start at our business loans hub.
How do you qualify for a small business loan?
Qualifying is less about ticking a fixed checklist and more about answering three questions a lender asks of every SME.
1. Can the business repay?
For unsecured lending this is the big one. Lenders look at your recent business bank statements to see regular income, how much is left after outgoings and whether the account is stable. A business with steady deposits and few dishonours is in a strong position.
2. What happens if it can’t?
This is where security comes in. If you own residential or commercial property, a lender can take a mortgage over it, which lowers their risk and widens your options. With property security, no cash flow or financial records are needed, and bad credit is OK.
3. Is anything already competing for your cash?
Lenders check your IRD position, existing loans and any other finance. GST or PAYE arrears don’t automatically mean no, but they need to be disclosed and planned for. A loan that clears tax arrears can be part of the solution.
What to have ready
- NZBN or Companies Office details, and how long you’ve been trading
- Recent business bank statements
- Your IRD position
- ID for each owner or director
- Details of any property you’re offering as security
- A one-line purpose and your repayment plan
Our guide to business loan requirements in NZ goes deeper on each item.
What does SME finance look like for different businesses?
These illustrative scenarios show how purpose and security steer the choice.
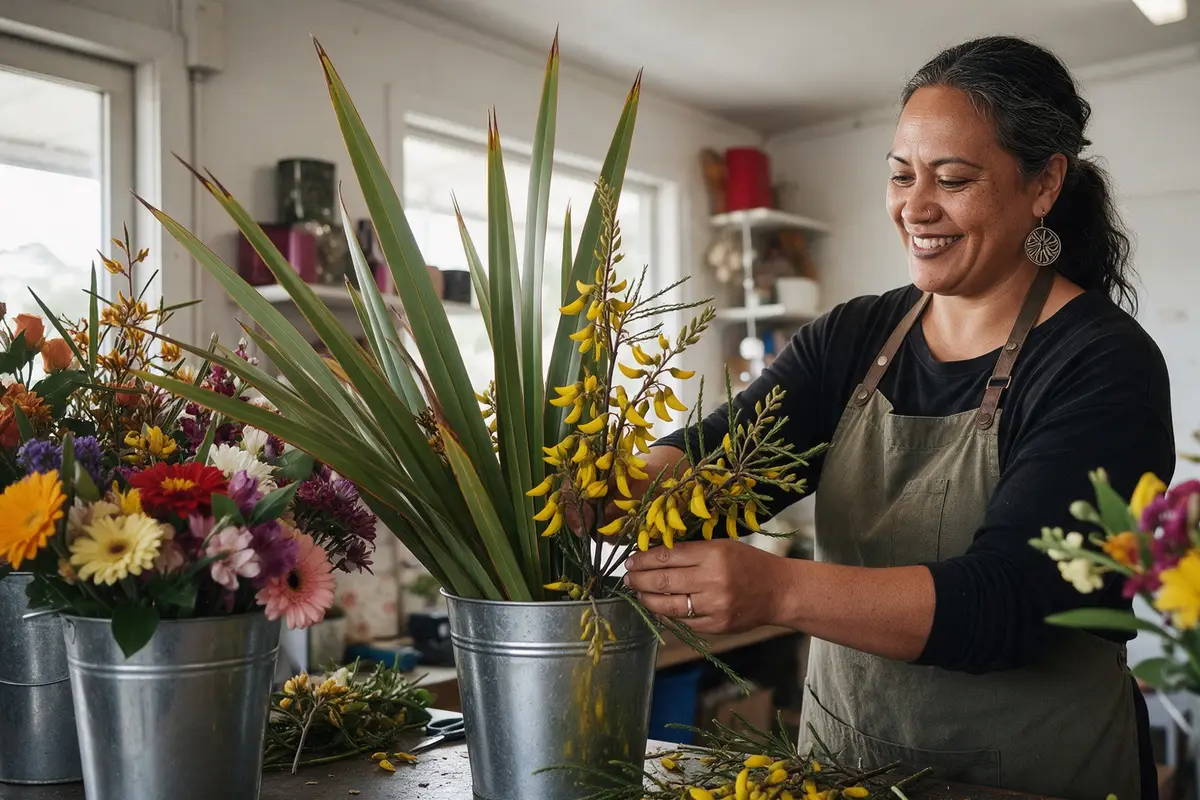
A Whangārei florist expanding into weddings. She needs a chiller, a second van and a website upgrade, around $45,000 in total. Her shop trades steadily year-round, so an unsecured loan repaid weekly from takings is a clean fit.
A Palmerston North electrician taking on two apprentices. Wages and tools come before the extra revenue does. A working capital loan smooths the first few months while the bigger crew gets up to speed.
A Hawke’s Bay winery supplier with a big export order. Raw materials must be bought now, but the buyer pays on 90-day terms. With a strong order and equity in the owners’ home, a second mortgage funds the order without touching the bank’s first mortgage.
A Queenstown tour operator before the ski season. Vehicles need servicing and staff need hiring before a single ticket sells. A short unsecured loan bridges the pre-season and is repaid from winter bookings.
Secured or unsecured: which suits a small business?
Most SME loans fall into one of two camps, and the difference shapes everything from paperwork to speed.
| Unsecured SME loan | Property-secured SME loan | |
|---|---|---|
| Amount | $20,000 to $500,000 | $20,000 to $500,000 |
| What the lender relies on | Your trading, shown in bank statements | Equity in residential or commercial property |
| Paperwork | Bank statements, IRD position, ID | Property details and your repayment plan; no cash flow or financial records needed |
| Credit history | Considered, recent trading matters most | Bad credit OK |
| Best for | Established businesses with steady income | Larger needs, bad credit, or books that are behind |
| Effect on your home | None | A 1st or 2nd mortgage registered on the title |
There’s no universally better choice. A busy café with strong takings and no property may sail through on an unsecured loan. A contractor with a patchy year but solid equity at home may find a second mortgage faster and simpler. We look at both before recommending a route.
What mistakes do small businesses make when borrowing?
Most SME finance problems come from the way the loan was chosen rather than the loan itself. The ones we see most:
- Using a long loan for a short need. Funding a three-month stock build with a five-year loan means paying interest long after the stock has sold. Our short term business loans page explains when shorter is smarter.
- Leaving it until the last minute. A loan arranged before the crunch is easier to approve and usually better priced than one arranged after a supplier has stopped deliveries.
- Ignoring the IRD position. Unpaid GST or PAYE grows with penalties and interest. Lenders will see it anyway, so plan for it in the application.
- Applying to several lenders at once. Each enquiry can show on your credit file. One well-matched application is stronger.
- Borrowing a round number. Work out the real figure, including GST where it applies, rather than guessing high or low.
Bank or non-bank lender for a small business?
Banks can be a good fit for long-term, low-risk lending to businesses with years of clean accounts and plenty of time. Many SMEs don’t fit that mould, or can’t wait weeks for an answer. Non-bank and private lenders tend to move faster, accept more varied situations and focus on the deal in front of them. Our bank vs private lender comparison sets out the trade-offs side by side.
How much can a small business borrow?
LoansOne arranges small business loans from $20,000 to $500,000. Where you land in that range comes down to a few practical things:
- For unsecured loans, what your bank statements show you can comfortably repay alongside your existing commitments. Lenders size the loan so repayments don’t squeeze day-to-day trading.
- For property-secured loans, the value of the property, what’s already owed on it and how the loan will be repaid at the end of the term.
- The purpose. A loan to clear a $38,000 GST bill should be sized to that bill, not rounded up for comfort.
The business loan calculator helps you test what different amounts and terms mean for your repayments before you apply.
How much does a small business loan cost?
We don’t quote rates, because each loan is priced on the client’s individual circumstances. The main things that shape pricing for an SME:
- Security, with property-backed loans generally priced more keenly than unsecured ones
- Loan amount and term
- Trading strength shown in your bank statements
- Credit history, including defaults or IRD arrears
- How clear the repayment plan is
LoansOne works to get the sharpest rate available for your situation. When comparing any offer, look at the total amount you’ll repay, including fees, not just the headline rate.
Why do Kiwi small businesses use LoansOne?
- Fast. Start in about 30 seconds online. Next-day funding is possible, and many loans are paid out within 24 hours.
- No credit file mark to enquire.
- Matched to the right lender, not sprayed across dozens of them.
- Secured and unsecured options from $20,000 to $500,000, with bad credit considered.
- An expert reviews every application before a lender makes contact.
Next step
Know what you need the money for? That’s the hard part done. Apply in about 30 seconds, or call 09-888 5252 and we’ll help you pick the right type of small business loan for your situation.