The short answer
Choose a short term business loan when the money will turn back into cash within months, such as stock, a tax bill, a seasonal gap or a bridging need. Choose a long term loan for assets that earn over years, like machinery, property or buying a business. Matching term to purpose keeps repayments affordable and total cost down.
What’s the difference between a short term and a long term business loan?
A short term business loan is repaid quickly, typically within a few months to two years. A long term business loan runs for several years. The term changes three things that matter to every business owner: the size of each repayment, the total you pay over the life of the loan and how much flexibility you keep along the way.
Most comparisons stop there. The more useful question is which term fits the job the money has to do, because that is where businesses either get it right or end up refinancing in a hurry.
What is the golden rule for choosing a loan term?
Match the term of the loan to the life of what you’re funding, or to how long it takes the money to pay you back.
- Stock you’ll sell over summer: short term.
- An IRD bill you’ll clear from the next couple of quarters of trading: short term.
- A gap until a property sale settles: short term.
- An excavator that will work for the next decade: longer term, often through equipment finance.
- Buying out a business partner or buying commercial premises: long term.
Borrow long for a short need and you pay interest for years on money that was useful for months. Borrow short for a long need and the repayments strangle cash flow before the asset has earned its keep.
Short term vs long term business loans compared
| Short term business loan | Long term business loan | |
|---|---|---|
| Typical term | A few months to about 2 years | Several years |
| Size of each repayment | Larger | Smaller |
| Total interest paid | Usually less, money is out for less time | Usually more over the life of the loan |
| Approval | Often very fast | Typically more assessment |
| Best for | Cash flow gaps, stock, tax bills, bridging, quick opportunities | Machinery, vehicles, property, acquisitions, long-life upgrades |
| Main risk | Repayments squeeze cash flow | Paying long after the benefit has gone |
| How it’s repaid | Trading income, sale, contract payment or refinance | Scheduled repayments over time |
When is a short term business loan the better choice?
Short term finance shines when there’s a clear, near-term source of repayment. The money goes in, does its job and comes back out within the term.
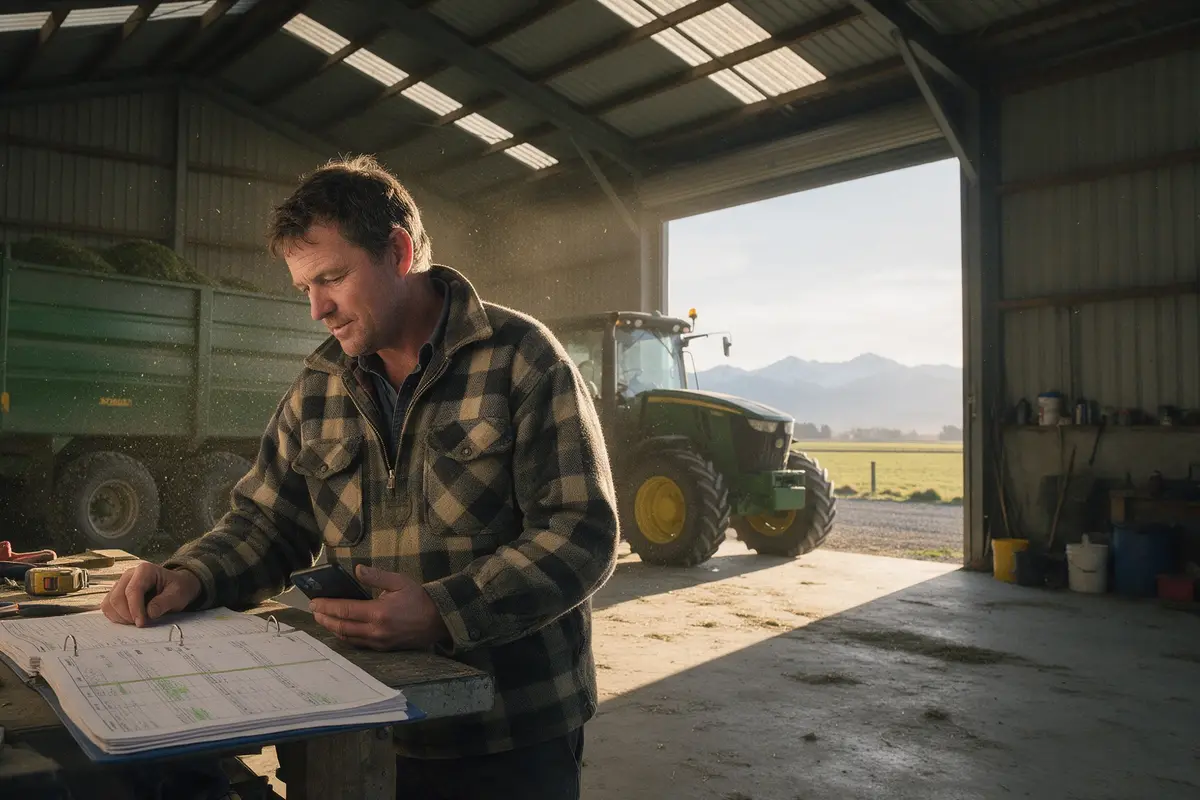
Seasonal peaks. A Canterbury dairy contractor gears up for spring: fuel, wages for extra operators, tyres and repairs on the silage gear. Clients pay on their usual terms, so the cash arrives weeks or months after the costs. A short term loan or working capital loan covers the gap and is repaid as invoices come in over the season.
Pre-season preparation. A Queenstown tour operator spends heavily before winter on vehicle servicing, staff training and marketing, then earns most of the year’s revenue between June and September. Borrowing short and repaying from peak takings keeps the shoulder season calm.
Tax and one-off bills. A GST or provisional tax bill is a short term problem. Spreading it over five years means paying for it long after it’s forgotten. A short term business loan clears it fast and stops penalties and use-of-money interest building with IRD.
Timing gaps around property. Waiting on a settlement or sale? Bridging finance is short term by design, with the sale as the exit.
When is a long term business loan the better choice?
Long term borrowing fits money that pays for itself slowly.
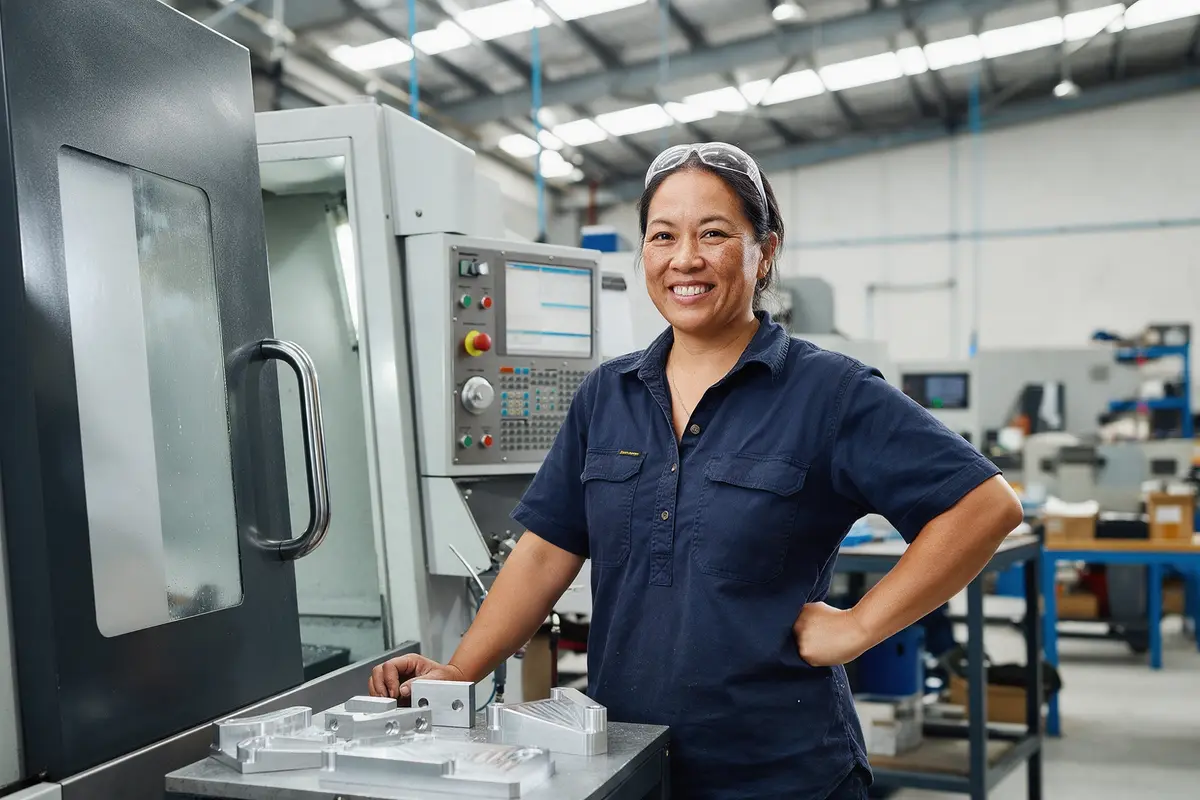
A Palmerston North engineering workshop buys a CNC machine to take on contract work for a larger manufacturer. The machine will be productive for many years and each job contributes a slice of profit. Squeezing the cost into 12 months would starve the business of cash. Spreading it over a longer term lets the machine pay its own way.
Other good long term fits:
- vehicles, fleet and heavy machinery
- buying a business or a partner’s shares
- commercial property and premises
- major fit-outs and refurbishments
- consolidating several expensive short loans into one manageable repayment
Does a shorter term always cost less?
Usually, but not always. Total interest is generally lower on a short loan because the principal is outstanding for less time. On the other hand, some short term products carry a higher annual rate, and fixed fees spread over a few months make up a larger share of the cost.
The only honest way to compare is to look at the total repayable over the time you’ll actually hold the loan. Our business loan calculator shows how changing the term moves both the repayment and the total. Every loan is priced on your individual circumstances, and LoansOne works to get the sharpest rate available for your situation, so we don’t publish example rates.
How does the loan term affect your cash flow?
Borrow the same amount over a shorter term and each repayment is bigger. That’s the trade-off. The test that matters is your weakest month, not your average one.
- Find your quietest trading month from the last year or two.
- Work out what’s left after wages, rent, suppliers, GST and PAYE.
- Check the proposed repayment fits inside that, with room to spare.
If the repayment only works in a good month, the term is too short. The cash flow gap calculator helps you map those quiet months before you commit.
Why does an exit strategy matter on a short term loan?
With short term lending, particularly property-secured loans like a second mortgage or caveat loan, lenders want to know how you’ll repay the full amount at the end. That’s your exit strategy. Typical exits include:
- trading income from a peak season
- the sale of a property, vehicle or other asset
- a large contract or retention payment
- refinancing to a bank once the business is back on its feet
A clear, believable exit makes approval faster and smoother. A vague one (“we’ll see how things go”) slows everything down.
What about interest-only and balloon structures?
Not every loan pays down evenly. Some short term property-secured loans are interest-only, with the full principal repaid at the end from a sale or refinance. That keeps the monthly outgoing low, but it only works if the exit is solid.
Some longer equipment and vehicle loans use a balloon, a larger final payment that lowers the regular repayments. It suits assets that hold their value well, because you can sell or refinance the asset to meet the balloon.
Both structures are useful tools. Both need a clear plan for that final payment from day one, so treat the end date as seriously as the start date.
Can you repay a long term loan early?
Often, yes. But check the terms before you sign. Some lenders let you repay early at no cost, while others charge a break fee. If there’s a real chance you’ll pay off early, from a property sale, an insurance payout or a refinance, negotiate that flexibility upfront.
A useful middle path for many businesses: take a longer term for affordable repayments, with the freedom to make lump-sum payments or clear the loan early when cash allows.
What are the most common loan term mistakes?
- Rolling short loans over and over. If you keep refinancing a short loan, the need was long term all along.
- Funding a long-life asset with a short loan. Repayments outpace what the asset earns.
- Stretching a tax bill over years. You’ll still be paying for last year’s GST when next year’s is due.
- Ignoring seasonality. Monthly repayments that suit summer can hurt in winter.
- Forgetting break fees. A long loan you plan to clear early can carry an unwelcome exit cost.
How LoansOne helps you choose the right term
LoansOne arranges unsecured business loans from $20,000 to $500,000, and fast, flexible 1st and 2nd mortgages for business from $20,000 to $500,000. An expert reviews every application and matches you to the lender whose terms suit your purpose, not just the first one to say yes. Your details aren’t sprayed across dozens of lenders, and starting an enquiry won’t mark your credit file.
Next step
Know what you need the money for and roughly when it will pay you back? Apply in about 30 seconds and we’ll match the loan term and lender to the job. Or call 09-888 5252 to talk it through.