The short answer
Transport business finance in NZ covers the gap between running costs like diesel, road user charges, maintenance and wages, and customers who pay on long terms. LoansOne arranges unsecured and cash flow loans from $20,000 to $500,000, truck and fleet finance, and 1st or 2nd mortgages for larger needs.
Why do transport operators run short of cash?
Freight is a volume business on tight margins. The trucks only earn while they roll, and every kilometre costs money now. Diesel goes on the fuel card this week, drivers get paid this week, but the customer’s invoice might not be paid until the 20th of next month, and big customers often stretch that further.
The real pressure points for Kiwi transport and logistics businesses:
- Road user charges: diesel vehicles and vehicles over 3.5 tonnes pay RUC, bought in advance in 1,000 km units (heavy electric vehicles are exempt until July 2027). A busy fleet burns through RUC licences fast.
- Fuel volatility: a jump in diesel prices hits before you can pass it on.
- Long payment terms: 20th of the month following is common, and larger customers may pay on 60 days or more.
- Compliance and licensing: goods service licences through NZTA, certificates of fitness and logbook obligations all have costs.
- Maintenance and tyres: a breakdown means repair bills and lost revenue at the same time.
- Growth: a new contract usually means another truck or trailer before the first invoice.
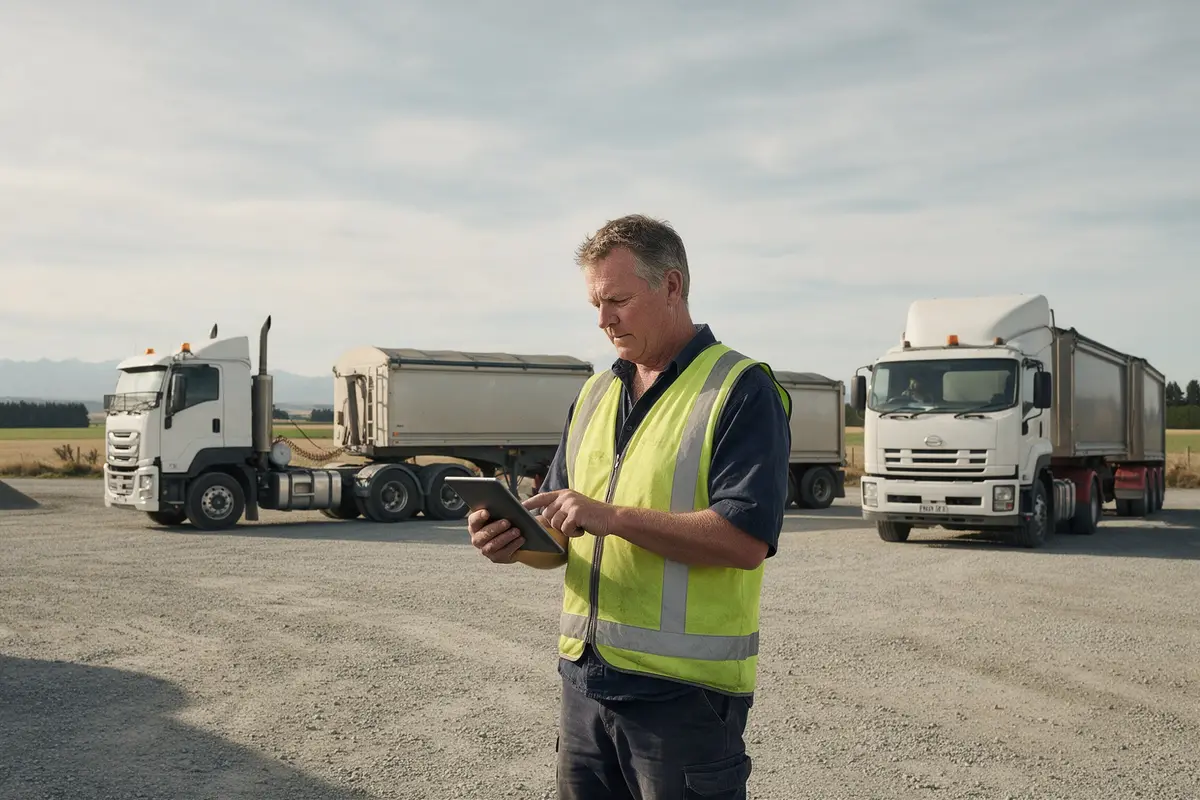
What do transport businesses typically fund?
- Trucks, trailers, vans and utes, new or used
- Fleet expansion to service a new contract
- Diesel, RUC and wages across the payment gap
- Major repairs, engine rebuilds and tyres
- Forklifts, warehouse racking and depot upgrades
- Telematics, tracking and dispatch systems
- Clearing IRD debt or GST arrears built up during a tight period
Which LoansOne options fit a transport business?
| Need | Option | Why it fits |
|---|---|---|
| Fuel, RUC and wages until invoices are paid | Unsecured business loan or cash flow loan | Fast, no property, $20,000 to $500,000 |
| Customers on long terms | Invoice finance | Unlocks cash in unpaid invoices |
| Trucks, trailers and vans | Truck and fleet finance | The vehicle secures the loan |
| Forklifts and heavy plant | Machinery finance | New, used and private sales |
| Larger sum, credit issues or accounts behind | 2nd mortgage | No cash flow or financial records needed, bad credit OK |
Pricing reflects your trading, security, the age and type of any vehicle, the term and purpose. Every loan is priced on your circumstances, and LoansOne works to get the sharpest rate available for your situation.
Illustrative example: a Waikato rural carrier
This is an illustrative scenario, not a real client.
A Waikato carrier running five units wins a regular contract carting stock feed and fertiliser for a rural merchant. The work justifies a sixth truck and another driver, but the merchant pays on the 20th of the month following, so the first payment is around seven weeks away. Meanwhile, the extra unit needs fuel, RUC, insurance and wages from day one.
The bank is slow to respond. The owner applies online and an expert reviews the contract, bank statements and existing fleet. The business is matched to a lender offering truck finance for the sixth unit, secured on the vehicle, plus an unsecured working capital loan to carry running costs until the contract payments settle into a rhythm. The new truck is on the road within days.
What do lenders look at for a transport business?
- Contracts and customers: who you cart for, how long you’ve worked with them, and how they pay.
- Bank statements: regular customer payments and how fuel and RUC costs track against income.
- Fleet: age, condition and value of your trucks and trailers, and any existing finance on them.
- Licensing and compliance: a current goods service licence and a clean operating record.
- Security: vehicles and property can support larger or lower-cost lending, and help if credit is patchy.
Before you sign a new contract, use the cash flow gap calculator to see how much you’ll carry before the first payment lands.
Truck finance or working capital: what do you actually need?
Many operators borrow for the truck and forget the cost of running it. A new unit on a new contract needs two kinds of money:
| Truck or fleet finance | Working capital or cash flow loan | |
|---|---|---|
| Pays for | The vehicle, trailer or equipment | Fuel, RUC, wages, insurance, repairs |
| Security | The vehicle, registered on the PPSR | Usually your trading, no property needed |
| Term | Matched to the working life of the asset | Short, matched to the payment gap |
| Risk if missed | Unit sits idle with no money to run it | Unit runs but squeezes everything else |
Getting both sorted at the start is often what separates a smooth new contract from a stressful one. For a closer look at the trade-offs, see asset finance vs unsecured loan.
How should you budget for RUC and fuel?
RUC and diesel are the two biggest variable costs for most operators, and both are paid before the customer pays. A few habits help:
- Track RUC purchases against hubodometer readings so you aren’t buying units in a panic.
- Build a fuel and RUC allowance into every quote, with a review clause on longer contracts.
- Watch for changes to the RUC system. The government is working toward moving more vehicles onto RUC and modernising how it’s paid, so keep an eye on NZTA updates.
- Keep a buffer that covers at least one full payment cycle of running costs.
Can owner-drivers and small fleets borrow too?
Yes. You don’t need a big depot to get finance. Owner-drivers contracted to a larger carrier, courier contractors and two- or three-truck operators all borrow for the same reasons as big fleets: a replacement unit, a major repair or a gap between paying for diesel and getting paid. Lenders look at your contract, your bank statements and the vehicle. If you trade as a sole trader or your accounts are behind, property-backed lending can fill the gap.
How can transport operators fund growth safely?
- Price new contracts with RUC, fuel and finance costs built in.
- Keep trucks on asset finance so working capital covers running costs.
- Use invoice finance when one or two slow-paying customers dominate your book.
- Replace tired units before repair bills and downtime eat the margin.
- Match the loan term to the working life of the vehicle.
Next step
Whether it’s a new truck, a fuel and RUC gap or a customer paying on 60 days, get funding moving today. Apply in about 30 seconds, free and with no mark on your credit file. An expert reviews your application and matches you to the right lender. Or call 09-888 5252.