The short answer
New Plymouth and Taranaki businesses can borrow $20,000 to $500,000 through LoansOne, unsecured or secured by a 1st or 2nd mortgage over property. Applications are made online or by phone, an expert reviews each one and matches it to a suitable lender, and next-day funding is possible.
How is Taranaki’s economy changing, and what does it mean for borrowing?
For two generations, oil and gas set the rhythm of business in New Plymouth. That is shifting fast. ANZ figures published in 2025 show that in 2008, oil and gas exports from Taranaki earned twice what dairy did. By 2024 the position had flipped, with dairy earning about three times as much as oil and gas.
Then, in September 2026, Methanex confirmed it would stop manufacturing at its Motunui methanol plant near Waitara at the end of February 2027. More than 200 direct jobs are affected, and the mayor has pointed to the engineering, electrical and instrumentation firms that service the plant as the next ring of impact.
Two things are true at once. Some Taranaki businesses face a hard few years. And the region still has real strengths: one of the highest GDP-per-person figures in the country, manufacturing output of about $1.7 billion in 2024, and a business community where roughly nine in ten firms employ fewer than 20 people. Small, adaptable businesses are exactly the ones that need fast, flexible finance during a transition.
Funding the pivot: engineering and energy service firms
If your workshop or crew built its book around gas, refining or petrochemicals, the next move is usually redeploying skills into growing sectors: dairy processing, wood processing and engineered timber, infrastructure, renewable energy and food manufacturing.
That costs money before it earns any. Common needs include:
- New machinery or tooling, for example stainless fabrication gear for food-grade work, often through equipment and vehicle finance
- Working capital to carry wages while you win and start new contracts
- Certifications, training and tendering costs
- Bridging slow payers: large clients often pay on 30 to 60 day terms, and invoice finance can unlock that cash
- Rolling several expensive short-term debts into one repayment with business debt consolidation
Our manufacturing business loans page covers plant, raw materials and big-order funding in more detail.
Dairy, farm services and the milk-price calendar
Dairy is now Taranaki’s biggest export earner, and the milk season drives cash flow for a long chain of businesses: farm owners and sharemilkers, contract milkers, vets, fencing and earthmoving contractors, feed suppliers, rural mechanics and transport operators feeding the large processing site at Whareroa near Hāwera.
The pressure points are predictable. Calving from late winter into spring means high costs and low milk income. Contractors gear up for silage and cropping in late spring and summer. And IRD bills can arrive just when the bank account is at its thinnest.
Our farm business loans page goes deeper on seasonal funding, machinery and stock.
City businesses: hospitality, retail and the summer events season
Away from the plant and the paddock, central New Plymouth has its own cash flow pattern. Cafés, bars and retailers along Devon Street and the foreshore, and around the Len Lye Centre and Govett-Brewster Art Gallery, lean on summer. The long-running TSB Festival of Lights in Pukekura Park brings crowds into the city through the holidays, and the Coastal Walkway keeps locals and visitors moving past the waterfront all year.
Builders, electricians and plumbers are the other big group, working across new subdivisions in Bell Block and the city’s northern and eastern fringes. Their pressure point is the gap between paying for materials and getting paid on progress claims.
Secured or unsecured: which suits a Taranaki business?
Most Taranaki owners end up choosing between two routes. Here’s how they compare.
| Unsecured business loan | 1st or 2nd mortgage (business purposes) | |
|---|---|---|
| Amount | $20,000 to $500,000 | $20,000 to $500,000 |
| What the lender relies on | Your trading through the business bank account | Equity in property you own |
| Financial records needed | Recent bank statements | No cash flow or financial records needed |
| Credit history | Matters more | Bad credit OK |
| Speed | Often the quickest | Fast, after title checks and any valuation |
| Best for | Steady traders who don’t want property tied up | Businesses in transition, lumpy income or past credit issues |
The full breakdown is on our secured vs unsecured business loans page. Property in New Plymouth suburbs such as Fitzroy, Merrilands and Bell Block, plus homes and lifestyle blocks across the province, is commonly used as security.
A Taranaki example: retooling a Bell Block fabrication shop
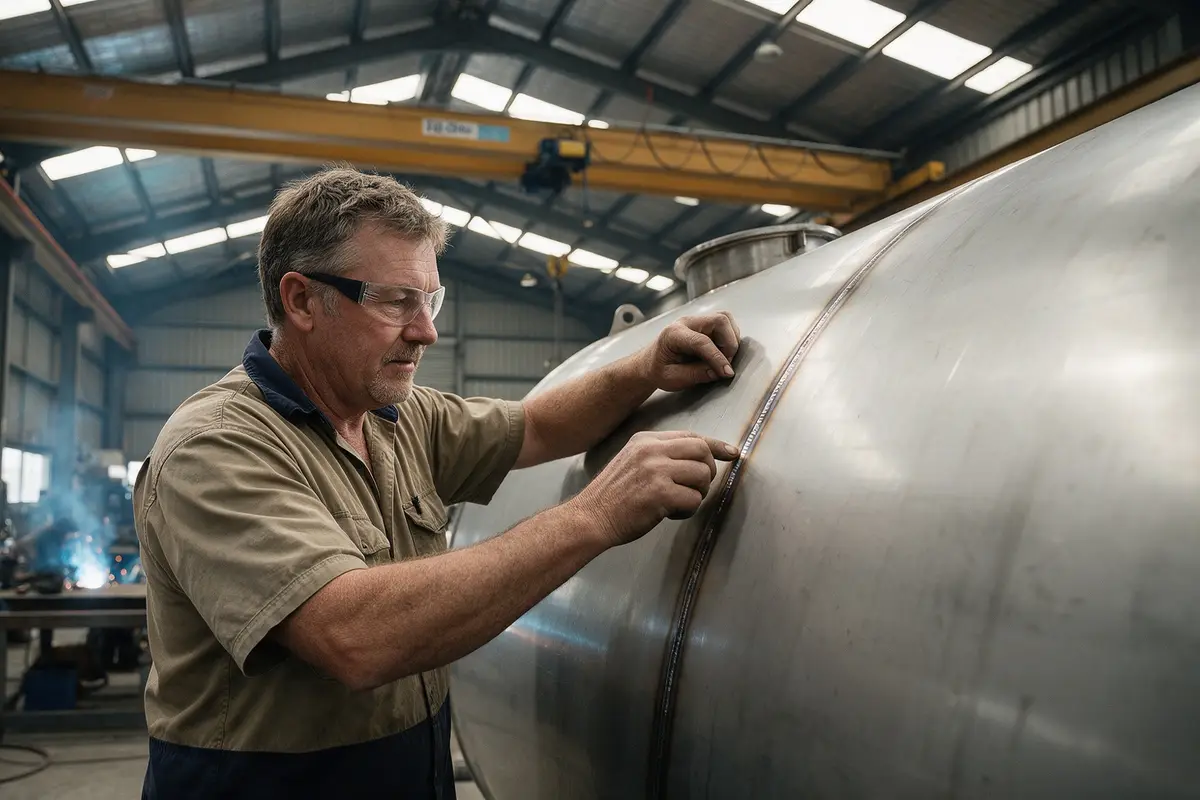
Picture a 12-person fabrication and maintenance business in Bell Block. A large share of its work has been shutdown and maintenance contracts in the energy sector. With that work set to shrink, the owner has lined up stainless steel fabrication for a food processor, but needs $150,000 for orbital welding gear, a second forklift and three months of wages while the new contracts ramp up.
Recent bank statements are softer than usual, which makes an unsecured lender cautious. A 2nd mortgage over the owner’s home in Merrilands, sitting behind the existing bank loan, relies on equity instead, needs no financial records and could be funded quickly. This is an illustrative scenario, not a real client.
Before signing anything, use our compare loan offers tool to line up total cost, term and security side by side.
Talking to LoansOne from Taranaki
LoansOne’s office is at 48 Shortland Street in Auckland. We serve New Plymouth and all of Taranaki by phone and online, from Waitara to Hāwera.
An expert reviews every application and matches it to the lender that suits your situation. Your details are not shopped around to dozens of lenders, and starting an enquiry doesn’t mark your credit file. Every loan is priced on your individual circumstances, and we work to get the sharpest rate available for your situation.
Next step
If your business is changing direction, the right funding can buy you the time to do it properly. Apply in about 30 seconds or call 09-888 5252 for a straight conversation.