The short answer
Manufacturing business loans in NZ fund plant and machinery, raw materials and the cash gap on large orders. LoansOne arranges unsecured loans from $20,000 to $500,000 assessed on trading cash flow, and 1st or 2nd mortgages from $20,000 to $500,000 secured on property, with equipment finance for machines. Next-day funding is possible.
Why do manufacturers run short of cash even when orders are strong?
Manufacturing has a built-in timing problem. You pay for steel, timber, resin or packaging before you make anything. You pay wages every week while the job is on the floor. Then you invoice, and your customer pays on the 20th of the month following, or on 60 or 90 days if they’re a large retailer or an overseas buyer.
So the busier you get, the more cash you need. A record month can leave the bank account thinner than a quiet one. That’s not bad management. It’s the shape of the industry.
The pressure points we see most in New Zealand manufacturing:
- Imported inputs paid in advance. Overseas suppliers often want a deposit or full payment before shipping, and exchange rate moves can lift the cost between order and arrival.
- Long debtor terms. Big customers set the terms, and small manufacturers rarely get to argue.
- Lumpy orders. A single contract can be worth months of normal turnover, and it needs funding up front.
- Machinery that ages out. When a key machine fails, production stops until it’s fixed or replaced.
- Tax timing. GST at 15% on large sales and provisional tax can land at the same time as a heavy materials bill.
What do NZ manufacturers typically borrow for?
Most manufacturing finance falls into three buckets: plant, inputs and growth.
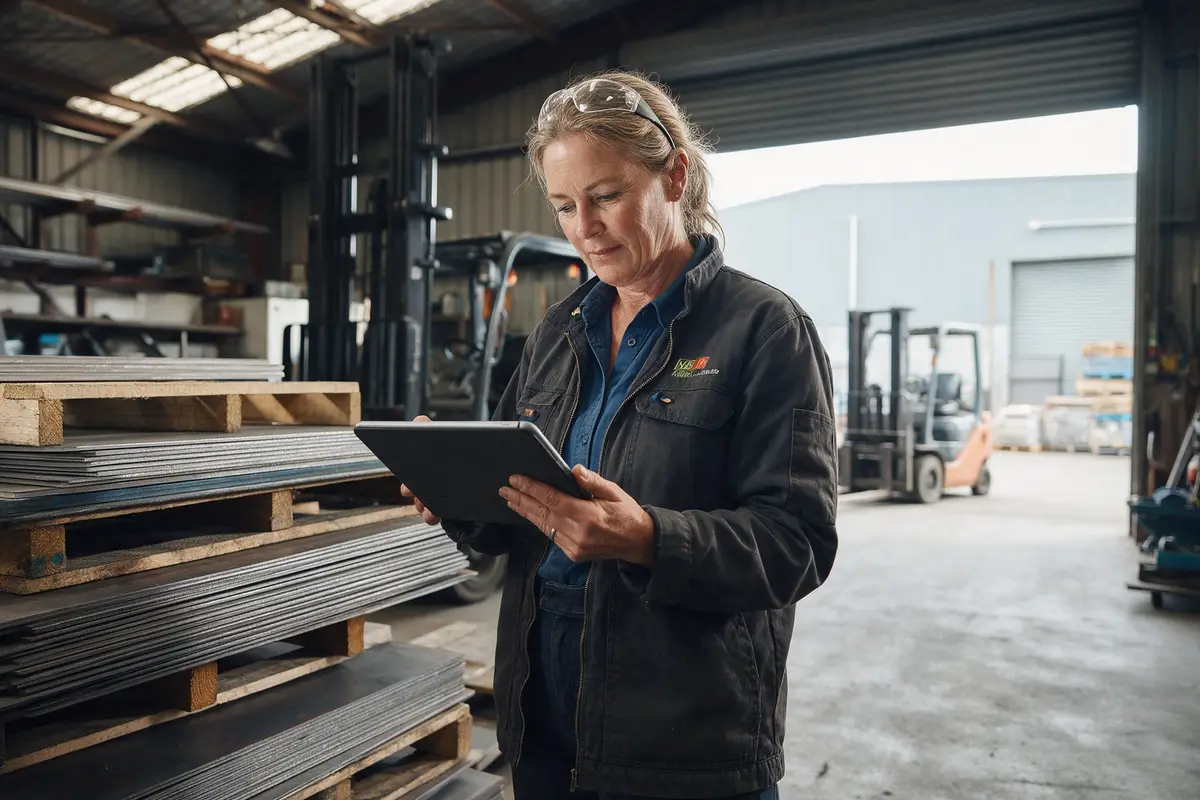
Plant and machinery. CNC routers and lathes, laser cutters, press brakes, injection moulders, kilns, packaging lines, forklifts and delivery trucks. Some of this is classic machinery finance, where the asset is the security.
Raw materials and stock. Buying in bulk at a better price, securing supply before a price rise, or filling a large order. If you import inputs, trade finance is worth understanding too.
Growth and the costs around it. A bigger unit, a factory fit-out, extra shifts, a new product line, or the electrical upgrade a new machine needs. These soft costs are often harder to fund with asset finance alone, which is where a business loan earns its keep.
Which LoansOne options suit a manufacturing business?
| Option | Best for | Security | What the lender relies on |
|---|---|---|---|
| Unsecured business loan, $20,000 to $500,000 | Materials, wages on a big job, soft costs of expansion | No real estate in most cases | Trading cash flow from bank statements |
| Cash flow loan | Bridging the gap between paying suppliers and getting paid | No real estate in most cases | Regular deposits and account conduct |
| 2nd mortgage, $20,000 to $500,000 | Larger needs when you own property with a bank loan on it | Property, behind your bank | The property; no financials needed, bad credit OK |
| 1st mortgage, $20,000 to $500,000 | Freehold or lightly geared property, or the bank is too slow | Property, ranked first | The property; no financials needed |
| Equipment finance | A specific machine or vehicle | The asset itself | The asset’s value and your trading |
If you’re torn between the last row and the first, our comparison of asset finance vs an unsecured loan walks through when each wins.
For ongoing material and wage gaps rather than one-off purchases, a working capital loan is usually the cleaner fit than stretching a machine loan to cover it.
Does Investment Boost change the maths on new machinery?
It can make a new machine more attractive. Under Investment Boost, a business can claim 20% of the cost of a new, or new to New Zealand, depreciable asset as an expense in the year it’s acquired, then depreciate the remaining 80% as usual. It applies to assets acquired from 22 May 2025, and imported machinery used overseas can still qualify. Second-hand assets already used in New Zealand don’t.
That tax benefit arrives when you file, not when you pay the supplier. Finance bridges that gap: you get the machine running now and the deduction lands later. Your accountant can confirm how it applies to your purchase.
What does manufacturing finance look like in practice?
Here’s an illustrative scenario, not a real client.
A Christchurch sheet-metal fabricator lands a contract to supply steel framing for a run of commercial builds. The work is worth roughly four months of normal turnover. The builder pays on the 20th of the month following each delivery, and the steel supplier wants payment on order.
The owner needs two things: steel for the first two stages, and a second press brake so the job doesn’t swamp the existing work.
The fix splits neatly:
- Equipment finance for the press brake, secured on the machine.
- An unsecured business loan for the first steel orders and extra wages, assessed on 12 months of solid bank statements and the signed contract.
Once the builder’s payments start flowing, the working capital loan is repaid from the contract income. The press brake keeps paying for itself long after the job ends.
If the fabricator had owned the factory building with a small bank mortgage on it, a 2nd mortgage could have covered both needs in one hit, with no financial statements required.
How do lenders view manufacturing businesses?
Lenders like manufacturers with a few things in their favour: repeat customers, contracts or purchase orders in writing, and machinery that holds value. They get cautious when one customer makes up most of the revenue, or when the bank account shows regular dishonours.
A few ways to strengthen your application:
- Have three to six months of business bank statements ready.
- Bring the order, contract or pro forma invoice behind the request.
- Know your numbers: what the money is for and how the job repays it. Our cash flow gap calculator helps you size the shortfall.
- Be upfront about any IRD arrears. They’re common, and lenders handle them better when they hear about them early.
Every loan is priced on your circumstances: the security, your trading, your credit history and the term. LoansOne works to get the sharpest rate available for your situation, and we don’t spray your details across dozens of lenders.
Next step
If a machine, a materials bill or a big order is putting pressure on your cash, apply in about 30 seconds. It’s free, it doesn’t mark your credit file, and an expert reviews every application before matching you with the right lender. Prefer to talk it through? Call 09-888 5252.