The short answer
Nelson and Tasman businesses can borrow $20,000 to $500,000 through LoansOne, unsecured or secured by a 1st or 2nd mortgage over property. Applications are made online or by phone, an expert reviews each one and matches it to a suitable private lender, and next-day funding is possible.
Why do Nelson Tasman businesses need a different kind of lender right now?
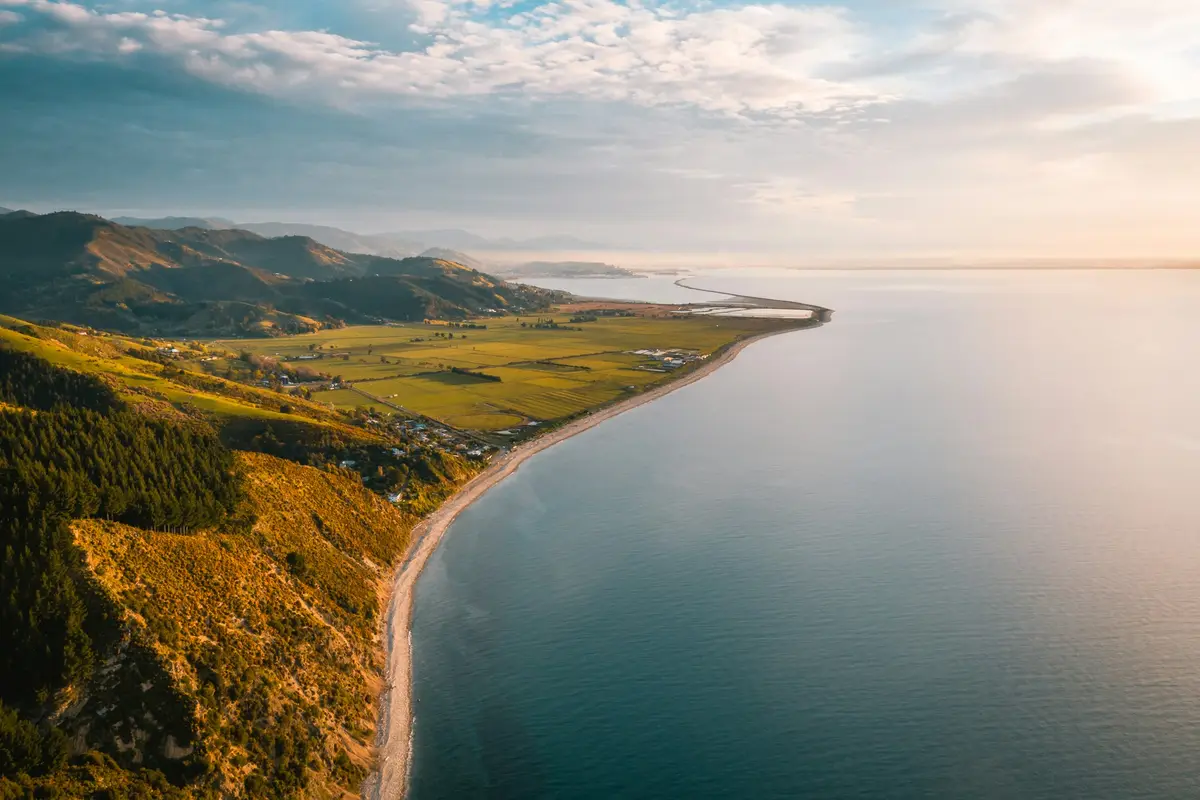
The top of the south has had a rough run. The winter floods of 2025 closed roads, damaged orchards and homes and cut off parts of Tasman for days. Around the same time, the region absorbed closures at a sawmill and a seafood processing plant and a string of smaller job losses. Local leaders called it one of the toughest stretches the region had seen.
None of that means Nelson businesses are bad bets. It means banks are often slower and more cautious here than they need to be. Owners who have traded well for years find themselves waiting weeks for an answer, or getting a polite no because their sector is “under review”.
That is where a private or non-bank lender earns its keep. They look at your business and your security as they are today, decide quickly and fund fast. LoansOne matches Nelson and Tasman owners with the lender that fits, from $20,000 to $500,000.
What industries keep Nelson and Tasman moving?
The region’s own economic agency groups its strengths into five areas, and almost every local business connects to at least one of them.
- The blue economy. Port Nelson is home to one of New Zealand’s busiest fishing fleets, with seafood processing, aquaculture and marine engineering clustered around it.
- Forestry and wood processing. Plantation forests across the region feed sawmills and Nelson Pine’s panel plant at Richmond.
- Food, beverage and horticulture. Apples and pears on the Waimea Plains and around Motueka, the country’s main hop-growing area, vineyards, craft breweries and specialty food makers.
- Science and technology. The Cawthron Institute anchors a cluster of research, marine science and tech businesses.
- The visitor economy. Three national parks, Abel Tasman, Kahurangi and Nelson Lakes, plus Golden Bay and a busy regional airport.
Underneath all of that sits a deep layer of small businesses: builders, electricians, cafés, retailers and professional firms in Nelson city, Stoke, Richmond and Motueka. The vast majority of the region’s businesses are small, which is exactly who LoansOne is set up to help.
Which loan fits which Nelson business?
There’s no single “Nelson loan”. The right product depends on what you need the money for and what you can offer as security.
| Nelson Tasman business | Common funding need | Loan types worth looking at |
|---|---|---|
| Marine engineering or fishing services near the port | Parts stock, workshop machinery, wages while awaiting fleet payments | Unsecured business loan, asset finance |
| Orchard, hop or vineyard operation | Harvest labour, sprays, machinery, flood repairs | 2nd mortgage, equipment finance, working capital |
| Builder or trades firm in Richmond or Stoke | Materials, plant, gaps between progress payments | Cash flow loan, unsecured loan |
| Café, brewery or accommodation provider | Fit-out, pre-summer stock and staff | Unsecured loan, 1st or 2nd mortgage |
| Owner with credit history problems | Any business purpose | 1st or 2nd mortgage, where bad credit is OK |
If you’re not sure which way to go, the loan matcher gives you a quick steer, or just talk to the team.
Can I borrow against property in Nelson or Tasman?
Yes. Property in Nelson city, Stoke, Richmond, Māpua and Motueka is still strong security, and using it can unlock more money, faster, than lending based on trading alone.
A second mortgage sits behind your existing bank loan, so your bank mortgage stays where it is. A private first mortgage can step in when the bank won’t. Both are available for business purposes from $20,000 to $500,000, with no cash flow or financial records needed.
After the floods, lenders pay closer attention to slips, flood zones and insurance, so expect questions if your property is on a hillside or near a river. They will check the title through LINZ and may order a valuation. A well-insured, undamaged property is usually straightforward.
A Nelson scenario: the marine engineer and the busy season
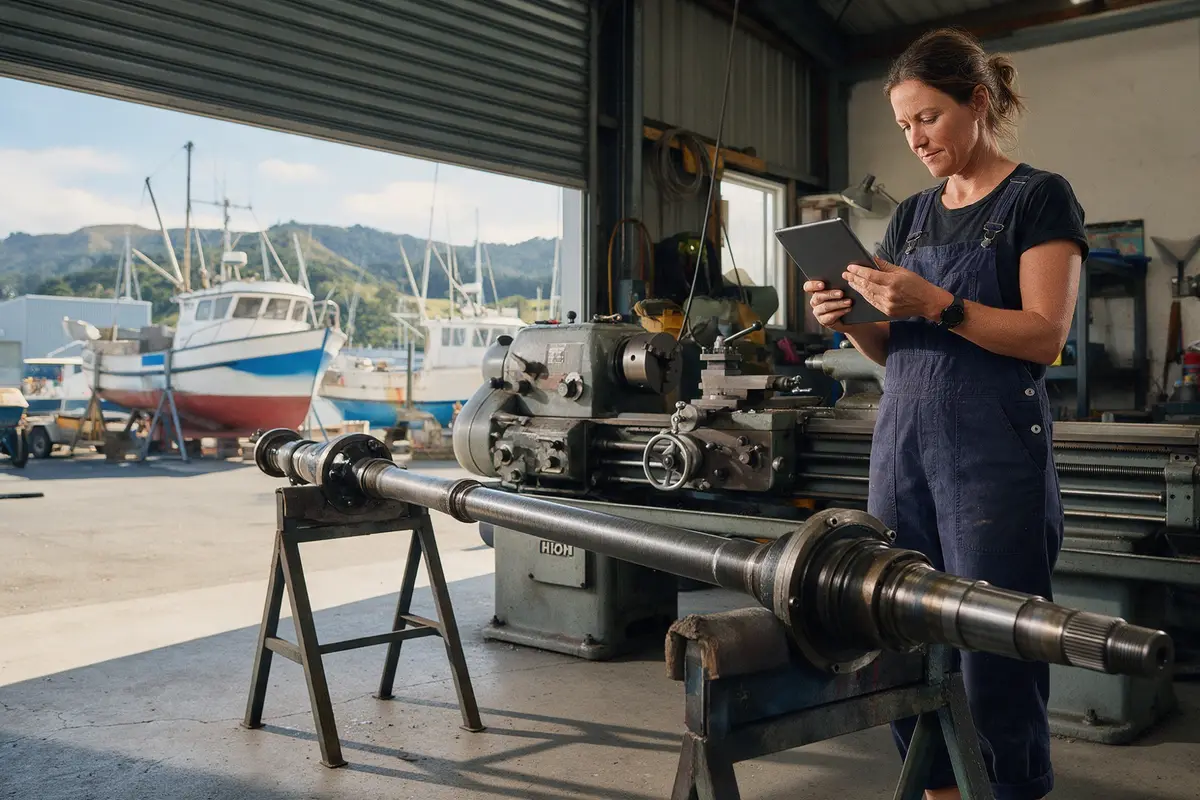
Consider a small marine engineering firm in the Port Nelson industrial area. It services inshore fishing boats and aquaculture vessels. Two large refit jobs land at once, and the owner needs $90,000 for parts, a second-hand lathe and six weeks of extra wages before the vessel owners pay.
The firm’s bank has been slow since the downturn and wants a full credit review. The owner can’t afford to turn the work away.
Because the business has steady deposits through its bank account, an unsecured loan assessed on 12 months of statements is a realistic option, with no property put on the line. If the owner preferred a larger buffer, a 2nd mortgage over their Stoke home would be another path. This is an illustrative example, not a real client.
If you’ve already been turned down elsewhere, our guide on what to do when the bank declines your business loan is a useful read, and our page on bad credit business loans covers past defaults and arrears.
How LoansOne works with Nelson owners from Auckland
LoansOne’s office is at 48 Shortland Street in Auckland. We serve Nelson Tasman by phone and online, so it makes no difference whether you’re in the city, out at Takaka or up the Motueka Valley.
You start online in about 30 seconds. An expert reviews your application, then the lender that best fits makes contact. Your details aren’t shopped around to dozens of lenders, and enquiring doesn’t mark your credit file. Every loan is priced on your individual circumstances, and we push for the sharpest rate available for your situation. Approval is never automatic, but you’ll get a clear, honest answer quickly.
Next step
If the bank is dragging its feet, don’t let the opportunity or the season slip past. Start your application in about 30 seconds or call 09-888 5252 for a straight conversation about your options.