The short answer
LoansOne arranges business finance for Christchurch and Canterbury owners from $20,000 to $500,000. Choose an unsecured business loan, or a fast 1st or 2nd mortgage that needs no cash flow or financial records. We work by phone and online, and next-day funding is possible in many cases.
Why is Christchurch a good place to be borrowing now?
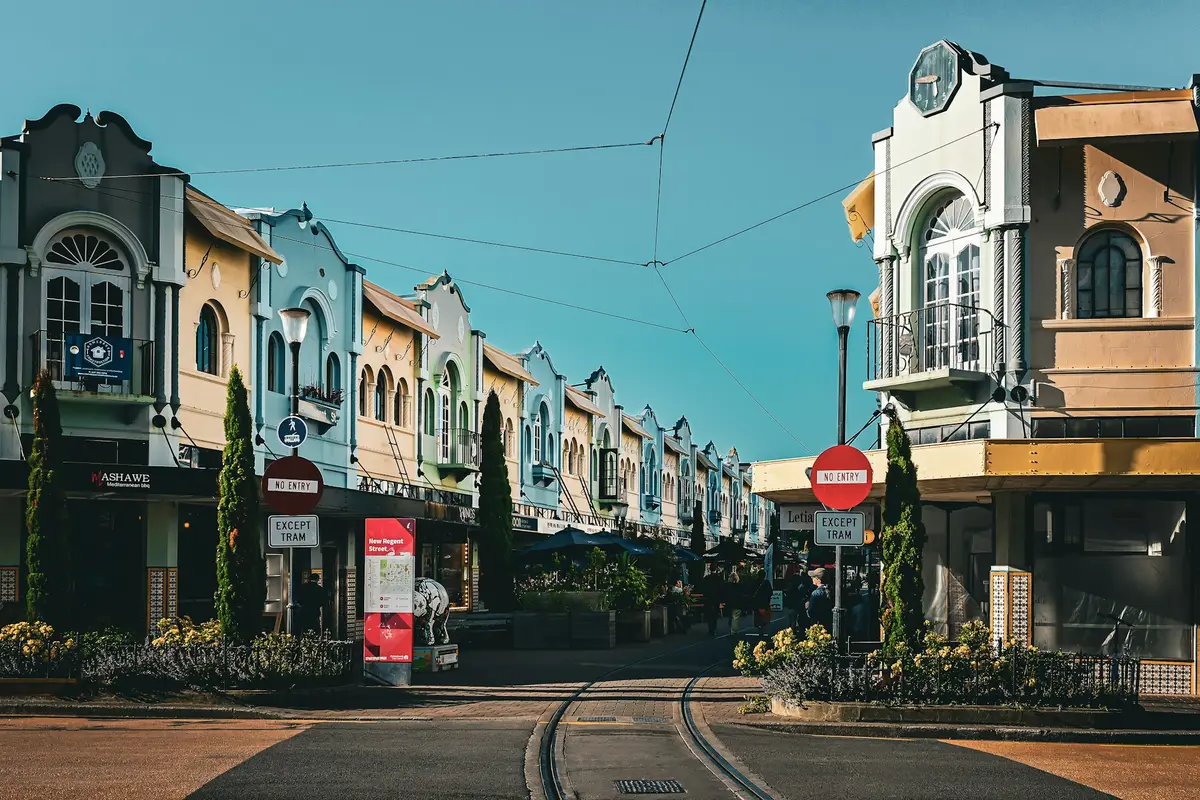
Christchurch has spent fifteen years rebuilding, and the payoff is visible. The central city is full of new offices, apartments and hospitality, and One New Zealand Stadium, Te Kaha, was handed over in late March 2026 after the best part of a decade and a half of planning and building. Concerts, test matches and conferences now bring crowds into the central city that local businesses have been waiting a long time for.
Around the city, Canterbury’s broad base of agriculture, manufacturing, logistics and engineering keeps the wider economy ticking. Selwyn and Waimakariri continue to grow, and new subdivisions mean steady work for builders, landscapers and every trade that follows them.
For owners, that mix creates a clear pattern: opportunity arrives fast, and the cash to grab it usually needs to arrive faster.
Christchurch business precincts and what they borrow for
| Precinct | What happens there | Typical finance |
|---|---|---|
| Central city and Victoria Street | Hospitality, professional services, retail | Fit-outs, working capital ahead of event days |
| Sydenham and Addington | Workshops, joinery, design firms, hospitality | Machinery, premises upgrades, stock |
| Hornby and Islington | Distribution, food processing, trade wholesale | Trucks, forklifts, larger stock orders |
| Wigram | Light industrial, trades, new commercial builds | Vans and tools, materials, new premises |
| Woolston and the Lyttelton corridor | Engineering, port-related services, freight | Plant, contract cash flow gaps |
| Rolleston (iZone) | Large-format warehousing and manufacturing | Equipment, staffing up for new contracts |
Industrial space in the city’s main precincts has stayed relatively tight compared with long-run levels, so businesses moving into new premises often face bond, fit-out and relocation costs all at once. An unsecured business loan can cover the move without waiting for the bank to finish its review.
What does Canterbury’s seasonal cycle mean for cash flow?
Christchurch businesses feel the seasons more than city businesses further north, because so much local trade connects back to farming and tourism.
- Late spring and summer: harvest and silage work keeps rural contractors and the engineering firms that service their machinery flat out, while wages and fuel bills peak before payments arrive.
- Autumn: arable and dairy payments flow back into town, lifting machinery dealers, trade suppliers and retail.
- Winter: ski traffic through Christchurch Airport helps hospitality, accommodation and rental operators, while construction slows on wet and frosty days.
- Event days: the stadium calendar now adds sharp spikes for caterers, bars, security firms and transport operators.
A working capital loan is often the tidiest way to carry wages and stock through the gap between doing the work and getting paid for it.
Beyond the city: Selwyn, Waimakariri and Mid Canterbury
Some of the region’s fastest growth is happening just outside the city boundary. Rolleston and Lincoln in Selwyn, and Rangiora and Kaiapoi in Waimakariri, have added thousands of homes, and the shops, childcare centres, gyms and trade businesses that follow. Further south, Ashburton and the Mid Canterbury plains support irrigation, dairy, arable farming and the machinery dealers, engineers and contractors who keep it all running.
These businesses often have strong turnover but lumpy cash flow, with big spending in spring and payments arriving months later. Our farm business loans page explains how lenders look at rural income.
Using Canterbury property as security
Christchurch property is more affordable than Auckland or Tauranga, but plenty of owners have built solid equity, particularly in established suburbs and in the newer growth areas of Selwyn and Waimakariri. That equity can back a fast, flexible 1st or 2nd mortgage for business purposes, with no cash flow or financial records needed and bad credit OK.
One local wrinkle: valuations in Christchurch carry the post-quake technical land category. Some lenders are more cautious with TC3 land because foundation work costs more. It seldom rules a property out, but it does change which lender is the right fit. That is exactly why matching matters. Our guide to borrowing against your house for business covers how lenders assess residential security.
A Christchurch example
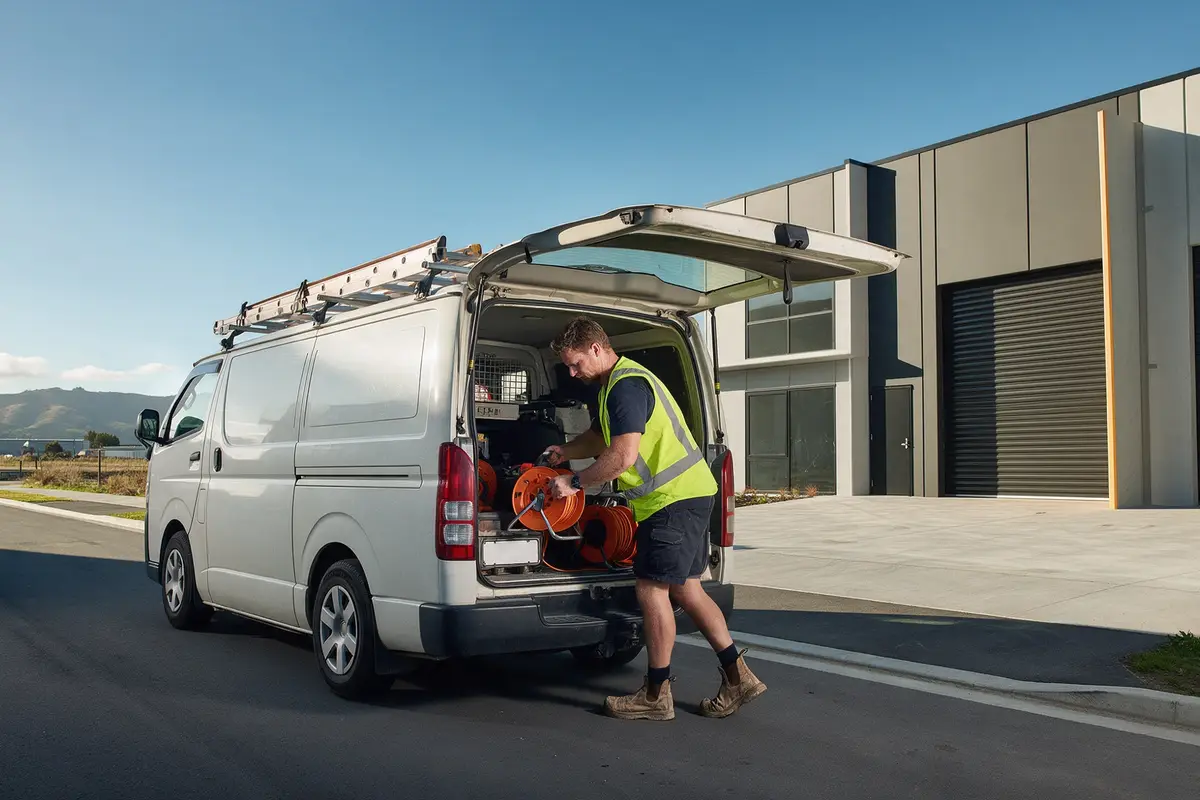
Here is an illustrative scenario. An electrical contracting firm based in Wigram wins a package of work on a new commercial build in Addington. It needs two more vans, a stock of switchboards and cable, and two extra apprentices for six months. The main contractor pays monthly, after a 20-day processing window.
The owners finance the vans through equipment and vehicle finance, where the vans themselves are the security. A separate unsecured loan covers materials and wages until the first progress claim is paid. The home stays out of it, and both facilities line up with the length of the contract.
Why Canterbury owners use LoansOne
You do not need a local branch to get local understanding. Whether your business is in a Sydenham workshop, a Hornby distribution shed or a new shop in Rolleston, what matters to a lender is your trading, your security and your plan to repay, and we know which lenders are comfortable with which mix. LoansOne works by phone and online from our Auckland office, and an expert looks at every application before a lender is involved. We match you to the right lender for your situation instead of spraying your file around. Starting an enquiry does not mark your credit file.
Every loan is priced on your circumstances, and we work to get the sharpest rate available for your situation. Want a quick read on where you stand first? Try the loan readiness check.
Next step
If a contract, a new site or a busy event season is coming, get the finance sorted before it arrives. Apply in about 30 seconds, free and with no mark on your credit file, or call 09-888 5252.