The short answer
LoansOne arranges business loans for Auckland companies from $20,000 to $500,000, either unsecured or secured by a 1st or 2nd mortgage over property. Our office is at 48 Shortland Street in the CBD. You can start online in about 30 seconds, and next-day funding is possible in many cases.
How do business loans work for Auckland companies?
Auckland runs on short timelines. A supplier in Penrose wants paying before the container clears, a fit-out in Ponsonby has to be finished before the landlord’s rent-free period ends, and a subcontractor in Albany is waiting on a main contractor who pays on the 20th of next month. Bank processes rarely match that pace.
LoansOne arranges business loans from $20,000 to $500,000 for Auckland owners through a panel of private and non-bank lenders. There are two main routes:
- Unsecured business loans, assessed mainly on how your business trades. No real estate security is required in most cases.
- Fast, flexible 1st or 2nd mortgages for business purposes. No cash flow or financial records needed, and bad credit is OK, because the property carries the weight.
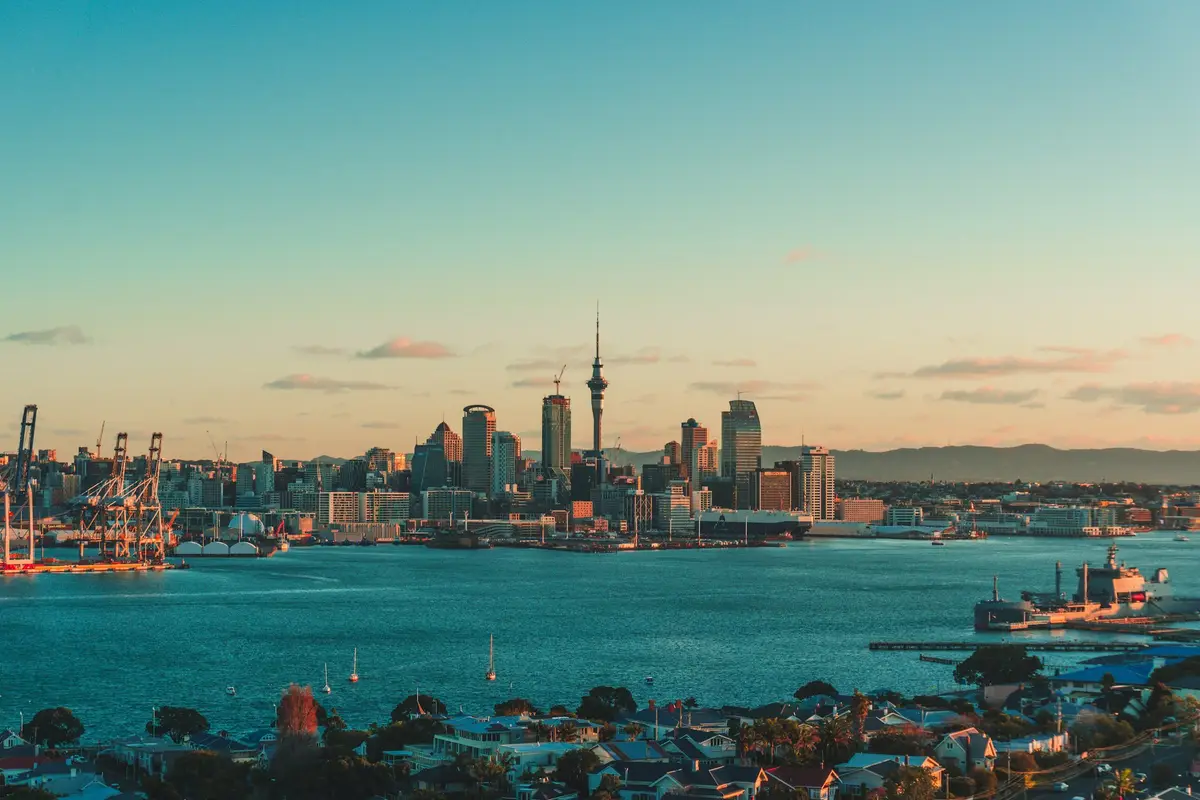
Our office is at 48 Shortland Street, a short walk from Britomart. We also serve every other region by phone and online, so if you have a site in Auckland and another in Hamilton or Tauranga, one conversation covers both.
Where does Auckland’s business borrowing come from?
Auckland is not one economy. Each business district has its own mix of trades, margins and cash flow patterns, and that shapes the finance that suits.
| District | Typical businesses | What owners commonly fund |
|---|---|---|
| CBD, Wynyard Quarter, Britomart | Professional services, hospitality, tech, retail | Fit-outs, working capital, partner buy-ins |
| Penrose, Onehunga, Mt Wellington | Wholesale, food production, engineering, trade suppliers | Stock, forklifts and racking, supplier deposits |
| East Tāmaki and Highbrook | Manufacturing, distribution, building products | Machinery, raw materials, large orders |
| Wiri, Manukau, airport precinct | Freight, logistics, cold storage | Trucks and trailers, fuel and contract gaps |
| Albany, Rosedale, Silverdale | Trades, light industrial, franchises, health | Utes and tools, new premises, expansion |
| Henderson, Avondale, New Lynn | Trades, automotive, food and retail | Workshop gear, vehicles, IRD arrears |
East Tāmaki alone is home to more than 2,000 businesses employing around 43,000 people, according to Business East Tāmaki’s 2024 profile. That kind of concentration means a lot of manufacturers and distributors competing on lead times, and lead times cost money up front. If that is your world, our manufacturing finance page goes deeper.
Can I borrow against Auckland property for my business?
Usually, yes. Auckland house values have eased from their 2021 peak, but long-time owners in suburbs like Mt Albert, Howick or the North Shore often hold substantial equity. That equity is the fastest key to a property-secured loan.
A second mortgage sits behind your bank, so your existing home loan and its terms stay as they are. The private lender relies on the title, a valuation and a clear plan to repay, such as a refinance, a sale or incoming contract payments. It is a common fix when the bank wants two years of finalised accounts and your accountant is still catching up.
If you do not own property, or would rather keep it out of the deal, an unsecured business loan is assessed on your bank statements and trading history instead.
When are Auckland businesses most stretched for cash?
A few pressure points come round every year:
- The Christmas shutdown. Many construction sites close from just before Christmas until mid-January, but wages, holiday pay and supplier accounts do not stop.
- Provisional tax. For a standard 31 March balance date, instalments fall on 28 August, 15 January and 7 May. The January one lands right in the quiet weeks.
- Summer stock builds. Retailers and hospitality venues load up before December and before the big summer events on the waterfront.
- Long payment terms. Main contractors and large retailers paying on 60 or 90 days leave smaller suppliers funding the gap.
Change brings its own costs too. The City Rail Link opened on 13 September 2026, and CBD retailers and hospitality owners near the new stations are now weighing refits and longer hours to catch the extra foot traffic. A working capital loan is often the cleanest way to fund that kind of push without draining the account you pay wages from.
What does this look like in practice?
Here is an illustrative scenario. A family-owned aluminium joinery manufacturer in East Tāmaki wins a supply contract for a townhouse development in Flat Bush. The builder pays on 60-day terms, but the extrusion supplier wants payment within 20 days and the order is three times their normal volume.
Their bank is supportive but slow, and their latest accounts are still with the accountant. The owners have equity in their Howick home, so a 2nd mortgage covers the materials and extra labour. When the first progress payment arrives, they start reducing the loan, and the whole facility is repaid as the contract finishes. No new bank paperwork, and the main home loan was never touched.
Why use a commercial broker in Auckland?
Auckland has no shortage of lenders. The hard part is knowing which one will say yes to your file, quickly, without leaving a trail of credit enquiries behind you.
LoansOne does not spray your application across dozens of lenders. An expert reviews it first, then matches you to the lender most likely to suit your situation, whether that is trading strength, property equity or a credit history with a few marks on it. Starting an enquiry does not mark your credit file.
Pricing is set on your individual circumstances, never from a rate card. What drives it is the security offered, the term, your trading record and how clear the exit is. We work to get the sharpest rate available for your situation. If you are holding more than one offer, our compare loan offers tool helps you see the true cost side by side.
Next step
Whether you run a café on Karangahape Road or a fleet out of Wiri, the quickest way to know your options is to apply in about 30 seconds. It is free and does not mark your credit file. Prefer to talk it through? Call 09-888 5252 or drop into 48 Shortland Street.