The short answer
Whangārei and Northland businesses can borrow $20,000 to $500,000 through LoansOne, either unsecured or secured by a 1st or 2nd mortgage over property. You apply online or by phone, an expert reviews your situation and matches you to a suitable lender, and funding can arrive in as little as 24 hours.
Northland’s economy in 2026: from refinery town to port and marine hub
For decades, Marsden Point meant one thing: the refinery. When refining stopped in 2022 and the site became a fuel import terminal, Bream Bay lost a large slice of its economic output almost overnight. Northland Regional Council estimates put the area’s GDP drop at well over half.
The story since then is more hopeful. A wave of large projects has been planned or proposed for Bream Bay, including expansion of Northport’s container capacity, a rail link to the port, a dry dock and a large solar farm at Ruakākā. Each one means work for local civil contractors, engineers, electricians, hire firms, caterers and accommodation providers.
Around that, Whangārei’s economy rests on familiar foundations:
- Forestry and logs, much of it exported through Northport
- Dairy and dry-stock farming across the wider region
- Marine industry, with boat building, refit and engineering businesses around Port Whangārei and the Town Basin
- Horticulture, from avocados in the north to kūmara around Dargaville
- Tourism, from the Tutukākā coast and Poor Knights to the Bay of Islands
- Health, education and public services, which give the city a stable employment base
Who borrows in Whangārei, and what for?
Lenders don’t treat Northland as one market. Here’s how local demand tends to break down.
| Sector | Where you’ll find them | Common funding need |
|---|---|---|
| Civil, building and trades | Port Road, Kioreroa Road, Ruakākā | Excavators, trucks, materials, wages between progress claims |
| Marine engineering and boat building | Port Whangārei, Town Basin | Workshop equipment, parts, refit jobs paid on completion |
| Forestry and logging | Rural Northland, Northport supply chain | Machinery repairs, harvest crews, cash flow when log prices dip |
| Retail and hospitality | CBD, Kensington, Onerahi, Tutukākā | Fit-outs, stock before summer, staff |
| Farming and horticulture | Kaipara, Far North, Hikurangi | Seasonal inputs, machinery, orchard development |
For contractors chasing the Bream Bay work, the construction and trades page covers progress payments and retentions in more detail, and heavy equipment finance explains funding for diggers, loaders and trucks.
How does Northland’s summer spike affect cash flow?
Northland’s visitor season is short and intense. Regional council data shows about a quarter of domestic visitor spending lands in December and January alone, and Aucklanders account for close to half of it.
That pattern ripples well beyond tourism. Cafés, bottle stores, boat services, fuel stops, holiday rentals and even builders racing to finish baches before Christmas all feel it. The common problem is that you pay for stock, staff and repairs in October and November, then earn it back in January.
A short-term business loan of three to twelve months, repaid once the season’s takings are in, can be a tidy fix. Use the business loan calculator to test repayments against your quieter months.
Can I use Northland property as security?
Yes. Homes, commercial buildings, lifestyle blocks and farms with general land titles can all support a 1st or 2nd mortgage for business purposes, from $20,000 to $500,000. No cash flow or financial records are needed, and bad credit is OK.
A few Northland-specific points:
- Rural and lifestyle property is common security here. Lenders will look at access, location and the condition of buildings when deciding how much to lend.
- Māori freehold land generally can’t be mortgaged like general land, so private lenders rarely take it as security. An unsecured loan or a mortgage over other property is usually the better path.
- Speed matters. A caveat loan can sometimes be registered faster than a full mortgage when time is very tight.
A Whangārei example: the Bream Bay contractor
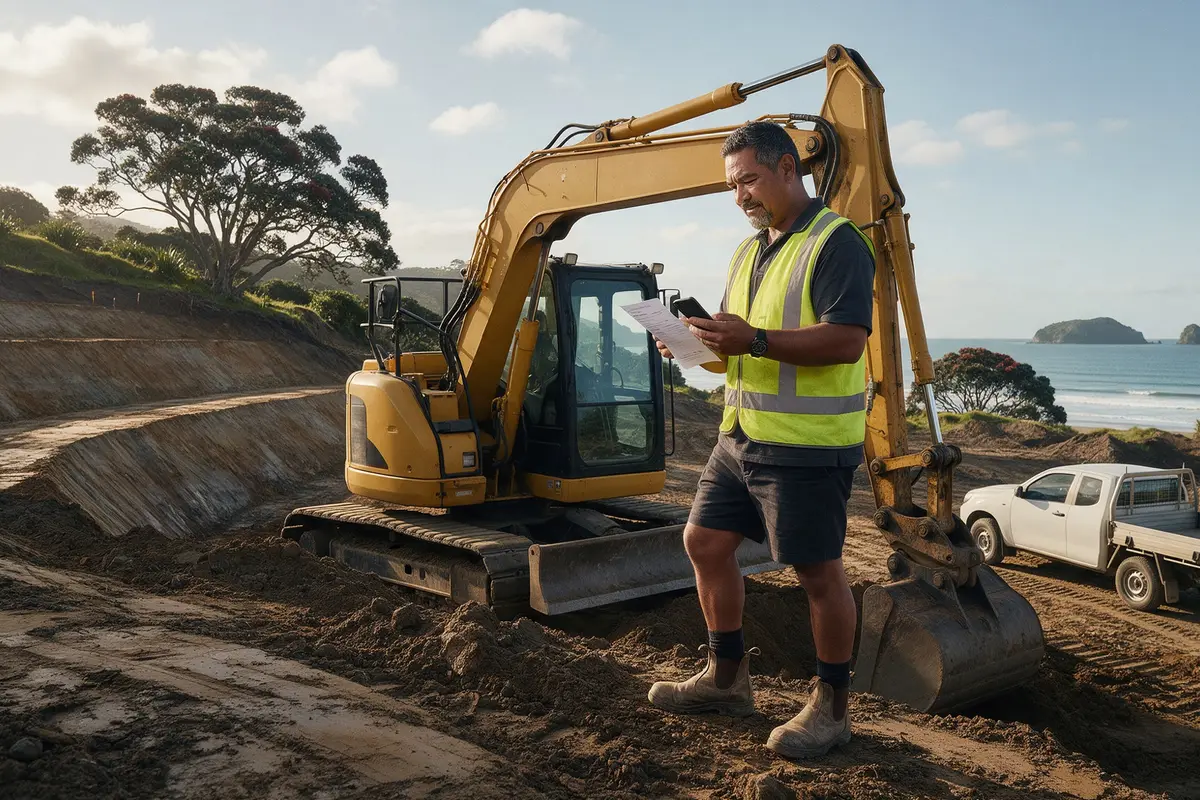
Imagine a three-person civil contracting business based in Ruakākā. It has been offered subcontract earthworks tied to one of the Bream Bay projects. To take it on, the owner needs a second excavator and a tip truck, plus enough cash to cover two months of wages before the first payment claim is paid. The total comes to $210,000.
The bank wants audited accounts the business doesn’t have, and the start date is four weeks away.
A realistic structure might combine finance on the machinery with a 2nd mortgage over the family home in Whangārei for the working capital, which doesn’t depend on financial statements. Alternatively, if the business’s bank statements show strong turnover, an unsecured loan could cover part of it. This is an illustrative scenario, not a real client, and the right mix depends on the full picture.
What helps a Northland application get approved?
Lenders want the same basics everywhere, but a few things matter more in Northland:
- Show the full year. Twelve months of business bank statements capture both the summer peak and the winter lull, which gives a fairer picture than the last quarter alone.
- Explain contract timing. If you’re tendering for Bream Bay or roading work, a letter of award or subcontract helps a lender see where repayments will come from.
- Be upfront about IRD. Overdue GST or PAYE is common after a slow winter. It can often be cleared as part of the same loan, so mention it early rather than hoping it won’t come up.
- Know your title. If you plan to use property, have the address and current lender handy so title checks can start straight away.
Finance from Auckland, without the drive over the Brynderwyns
LoansOne’s office is at 48 Shortland Street in Auckland, but you’ll never need to come in. We serve Whangārei, Kerikeri, Kaitāia, Dargaville and the rest of Northland by phone and online.
An expert reviews your application, then one lender that suits your situation makes contact. Your details aren’t fired out to a long list of lenders, and starting an enquiry doesn’t mark your credit file. Every loan is priced on your circumstances, and we work to get you the sharpest rate available for that situation.
Next step
Whether it’s a new contract, a summer rush or a bill from IRD, get the funding sorted before it’s urgent. Apply in about 30 seconds or call 09-888 5252 to talk it over.