The short answer
LoansOne arranges business loans for Tauranga and Bay of Plenty businesses from $20,000 to $500,000. Options include unsecured loans assessed on trading and fast 1st or 2nd mortgages that need no financial records. We serve the region by phone and online, and next-day funding is possible in many cases.
What drives the Bay of Plenty economy?
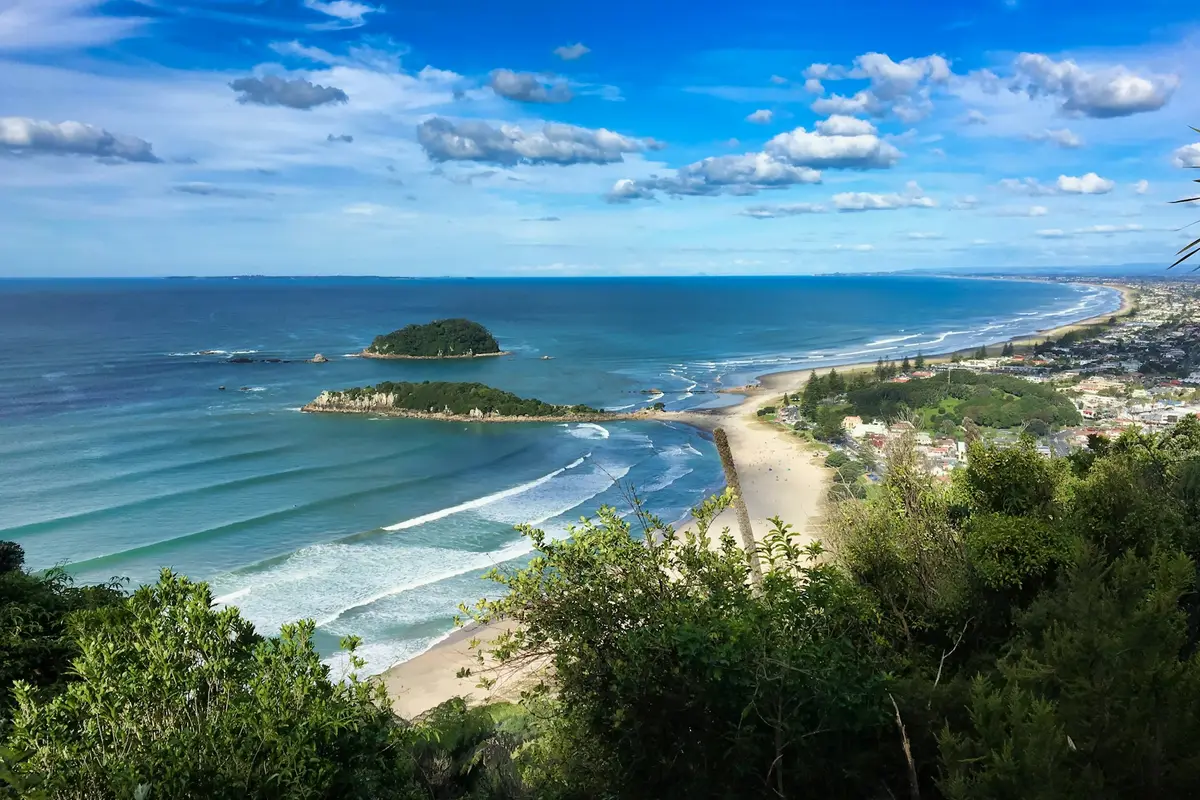
Tauranga has grown quickly. ANZ’s 2026 regional spotlight report notes the city’s population roughly doubled between 1996 and 2025, to about 161,000, putting it on track to become New Zealand’s fourth-largest city. Three engines sit behind that growth.
- The port. Port of Tauranga handles about a third of New Zealand’s cargo by tonnage and close to half of the country’s containerised exports, according to the same report. Freight, warehousing, engineering and customs businesses cluster around it.
- Kiwifruit and horticulture. The region grows around 80% of New Zealand’s kiwifruit. Orchards around Te Puke, Katikati and the Western Bay feed packhouses, coolstores, contractors and a large seasonal workforce.
- Construction. A growing population needs homes, schools, roads and commercial space, from Pāpāmoa East to The Lakes and Ōmokoroa.
For local owners, that means plenty of opportunity, and costs that often land well before the income does.
Tauranga’s business zones at a glance
Mount Maunganui and Sulphur Point. Industrial land around the port, with engineering shops, freight operators, fuel and bulk handling firms.
Tauriko and the western corridor. A fast-growing business estate with warehousing, trade supply and manufacturing. Councils have enabled about 108 hectares of business land at Tauriko and a further 148 hectares at Rangiuru, near Te Puke, to meet long-term demand.
Te Puke and the Eastern Bay. The kiwifruit capital: packhouses, orchard contractors, irrigation and machinery dealers.
The CBD, Bethlehem and Pāpāmoa. Retail, hospitality, health and professional services serving a fast-growing population.
How the kiwifruit year shapes local cash flow
Many Tauranga businesses never touch a kiwifruit, yet still feel the harvest. When the crop is big, contractors hire, packhouses run extra shifts and spending ripples out to retail, hospitality and trade suppliers.
| Period | Orchard activity | What local businesses face |
|---|---|---|
| March to June | Harvest and packing | Peak wages, fuel, bins, transport and maintenance |
| July to September | Winter pruning | Contract crews busy, but revenue spread thin |
| October to December | Flowering, pollination, thinning | Spring prep spending, summer stock builds |
| Year-round | Coolstore and export shipments | Freight volumes swing with crop size and shipping schedules |
A working capital loan gives you cash to staff up for harvest without waiting for grower or packhouse payments to clear.
Funding construction in a fast-growing city
Population growth has kept Tauranga builders and subcontractors busy for years, but construction cash flow is rarely smooth. Main contractors pay on monthly claims, retentions are held back until well after completion, and materials have to be paid for on the supplier’s terms, not yours.
Common finance needs for Bay of Plenty trades include:
- Materials and wages for the first month or two of a new contract.
- Utes, vans, trailers and tools when you take on more staff.
- A larger yard or workshop in Tauriko or Pāpāmoa as the business grows.
- Clearing GST or PAYE arrears that built up during a slow patch.
Using Bay of Plenty property as security
Tauranga has long been one of New Zealand’s more expensive property markets, and many owners have held property through years of growth. That equity is one of the fastest routes to business finance.
A second mortgage for business purposes sits behind your bank loan, so your existing mortgage stays as it is. A fast first mortgage suits owners with clear title or who want to refinance. Both run from $20,000 to $500,000, need no cash flow or financial records, and bad credit is OK. Orchard and lifestyle properties can also be used, though they suit some lenders more than others.
A Mount Maunganui scenario
Here is an illustrative example. An engineering workshop near the port fabricates and repairs equipment for freight and bulk handling operators. A logistics customer asks for a run of custom trailer components and wants delivery in eight weeks, with payment 30 days after delivery.
The workshop needs steel, a second plasma cutter and overtime for its team. The cutter is funded through equipment finance, with the machine as security. An unsecured business loan covers steel and wages, and is cleared once the customer pays. The owners keep their home out of the deal entirely. Because each facility matches the life of what it pays for, the unsecured loan is gone within a few months while the cutter keeps earning for years. If the customer comes back with a second order, the workshop already has a lender who knows the business.
Why Bay of Plenty owners use LoansOne
You get an expert review of your application before any lender sees it, then a match with the lender most likely to suit your situation. We do not shop your details around, and enquiring does not mark your credit file. Builders and subcontractors can see how lenders treat progress payments and retentions on our construction and trades page.
Every loan is priced on your circumstances, and we work to get the sharpest rate available for your situation.
Getting ready before harvest or a big contract
The best time to arrange finance is before you need it. If harvest, a port contract or a building job is a few weeks away, gather photo ID, recent bank statements, details of any property you might use and a short note on how the loan will be repaid. Lenders respond fastest to a clear, complete picture. Our cash flow gap calculator helps you size the gap so you borrow what you need and no more.
Next step
If harvest, a port contract or a new site is coming up, sort the finance now. Apply in about 30 seconds, free and with no mark on your credit file, or call 09-888 5252.