The short answer
Queenstown Lakes businesses can borrow $20,000 to $500,000 through LoansOne, unsecured or secured by a 1st or 2nd mortgage over property. Operators in Queenstown, Frankton, Arrowtown and Wānaka apply online or by phone, an expert matches them to a suitable lender, and funding can arrive in as little as 24 hours.
What makes business finance in Queenstown different?
Queenstown Lakes is not like other regions. Tourism is the backbone: Destination Queenstown’s own figures put tourism at well over a third of all jobs in the district in 2023. Around it sits a large construction and property sector, a strong wine industry in Gibbston and Central Otago, and a service economy of builders, cafés, retailers, cleaners, transport firms and professional practices.
Three things shape how lenders see local businesses:
- Two peaks. Winter brings skiers to Coronet Peak, The Remarkables, Cardrona and Treble Cone. Summer brings hikers, cyclists, wedding parties and adventure seekers. Most operators earn the bulk of their money in those windows.
- Very high costs. Commercial rents, wages and especially staff housing cost more here than almost anywhere in New Zealand. Industrial space in the Frankton basin has long been in short supply.
- Valuable property. Many owners hold homes or commercial property with significant equity, which opens up secured options that move quickly.
The district is also bigger than Queenstown itself. Wānaka has its own year-round economy of builders, cafés, retail and outdoor operators, with a strong base of property owners. Arrowtown leans on hospitality, boutique retail and heritage tourism. The Gibbston Valley adds vineyards, wineries and the contractors who service them, and just over the district boundary Cromwell’s orchards and light-industrial firms serve the wider basin. Each of these places has its own rhythm, but they share the same pressures: costly staff, scarce commercial space and income that arrives in waves.
Good finance here is less about the size of the business and more about timing.
When do Queenstown businesses usually need funding?
The quiet months are when you spend. The busy months are when you earn. That gap is where most local borrowing happens.
| Period | What’s happening | What owners typically fund |
|---|---|---|
| April to May (shoulder) | Summer winds down, winter prep begins | Ski hire stock, vehicle servicing, staff recruitment and housing bonds |
| June to October (winter) | Ski season, school holiday spikes | Extra wages, consumables, fit-out touch-ups |
| October to November (shoulder) | Ski fields close, summer prep begins | Boats, e-bikes, tour vans, marketing, refurbishments |
| December to March (summer) | Peak visitors, weddings, events | Stock top-ups, casual staff, equipment replacement |
| After each peak | IRD bills land | GST and provisional tax when cash has already gone into the next season |
Run your own numbers through the cash flow gap calculator to see how big your shoulder-season hole really is.
What do Queenstown Lakes owners borrow for?
Across the district, the same handful of needs come up again and again:
- Vehicles and vessels: tour vans, coaches, 4WDs, jet boats and utes, often through equipment and vehicle finance
- Staff accommodation: bonds, leases, furniture or part of a property purchase
- Fit-outs and refurbishments for cafés, bars, retail and accommodation in the town centre, Frankton and Wānaka
- Buying a business: tourism operations and hospitality venues change hands regularly, and business acquisition finance is a common request
- Construction plant and materials for builders working on the district’s steady pipeline of homes and commercial projects
- Clearing IRD debt or GST after a big season
Our tourism business loans page goes deeper on vessel and vehicle funding and pre-season preparation.
Borrowing against high-value Lakes property
Property in Queenstown, Frankton, Lake Hayes, Arrowtown, Kelvin Heights and Wānaka is among the most valuable in the country. For a business owner, that equity can be the fastest route to funding.
A business loan against your house usually takes one of two forms:
- Second mortgage: sits behind your bank, so your existing home loan stays untouched. Useful when your bank deal is good and you don’t want to disturb it.
- Private first mortgage: replaces bank lending when the bank is too slow, wants more paperwork than you have, or has said no.
Both are available for business purposes from $20,000 to $500,000. No cash flow or financial records are needed and bad credit is OK. Lenders still check the title through LINZ, look at what’s already owed and may order a valuation, but the process is far quicker than a typical bank.
A Queenstown example: gearing up for summer
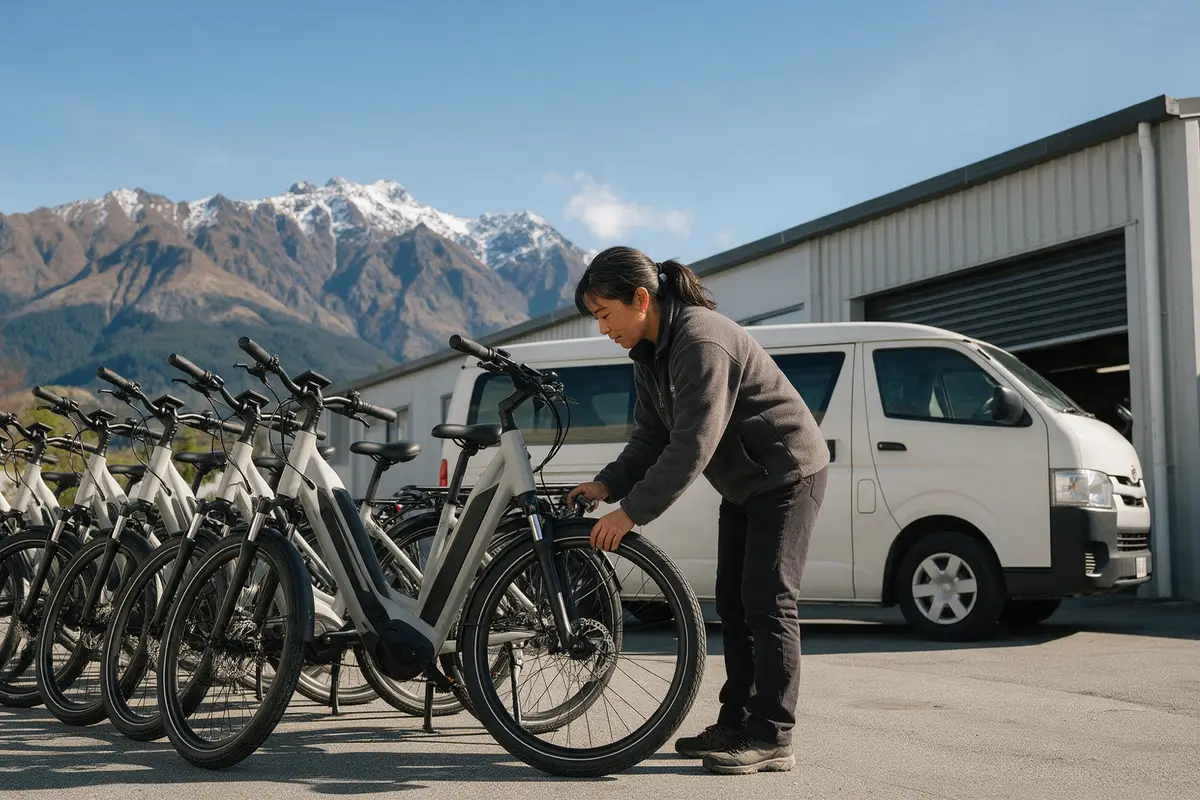
Picture an e-bike tour operator based in a Frankton industrial unit, running trips to Arrowtown and Gibbston. Winter is quiet. In October the owner wants to add 12 e-bikes, a second van and trailer, and to pre-pay staff housing for four summer guides. Total: $120,000.
The bank likes the business but wants to wait for year-end accounts, which won’t be ready until after Christmas. By then the season is half over.
Two options are realistic. An unsecured loan based on the past year’s bank statements works if the off-season months still show enough trading. Or a 2nd mortgage over the owner’s Lake Hayes Estate home, which doesn’t rely on accounts at all and can be in place within days. This is an illustrative scenario, not a real client.
Do you need a Queenstown-based broker?
Not really. What matters is speed, honesty and access to lenders who understand seasonal trade. LoansOne is based at 48 Shortland Street in Auckland and serves the Lakes District by phone and online, so you can deal with us from your office, your van or the top of the gondola.
Every application is reviewed by an expert and matched to one suitable lender. Your details are not shopped around to dozens of finance companies, and enquiring doesn’t touch your credit file. Pricing is set on your individual circumstances, and we work to get the sharpest rate available for your situation.
Next step
The best time to sort funding is before the next peak, not in the middle of it. Apply in about 30 seconds or call 09-888 5252 and talk to the team today.