The short answer
Tourism business loans in NZ help operators cover off-season costs, pre-season maintenance, vehicles, vessels and lodge upgrades. LoansOne arranges unsecured loans from $20,000 to $500,000 assessed on trading cash flow, and 1st or 2nd mortgages from $20,000 to $500,000 secured on property, with no financials needed. Next-day funding is possible.
Why is cash flow so seasonal in NZ tourism?
New Zealand tourism runs on two big clocks. The summer peak, roughly December to March, brings long-haul visitors from the Northern Hemisphere, Australians on holiday and Kiwis on the road. Then the ski season, roughly June to October, lifts places like Queenstown, Wānaka and the Central Plateau around Ruapehu while coastal operators go quiet.
Most operators earn the bulk of their year in one of those windows. The costs don’t follow the same pattern. Leases, insurance, loan repayments, vessel surveys, vehicle servicing and core staff all keep running through the quiet months.
The pressure points we see most:
- The off-season trough. Months of fixed costs with little coming in.
- Pre-season spend. Maintenance, marketing, new gear and hiring seasonal staff all happen before the first big booking pays.
- Delayed booking income. Bookings through agents and wholesalers can pay out after the trip runs, not before.
- Weather and events. A wet summer, a road closure or a cancelled cruise ship visit can wipe out a strong week.
- Big-ticket assets. Boats, coaches, 4WDs and lodge buildings need regular reinvestment to stay safe and appealing.
Our guide to seasonal business cash flow goes deeper on planning for the trough.
What do tourism businesses typically fund?
Pre-season preparation. Slipping and antifouling a vessel, servicing a fleet, replacing rafts, kayaks or e-bikes, and refreshing marketing before the season opens.
Vehicles and vessels. Tour vans, coaches, 4WDs, jet boats, catamarans and replacement engines. These are business assets and often suit equipment and vehicle finance, with the asset as security.
Lodges and accommodation upgrades. Bathrooms, heat pumps, decking, new rooms or a full refurbishment while guests are away.
Off-season working capital. Carrying core staff and fixed costs through the trough so you don’t lose good people before the next peak.
Growth. Buying another operator, adding a new experience or extending into the shoulder season to smooth income.
Which LoansOne options fit a tourism operator?
| Need | Usually fits | Notes |
|---|---|---|
| Pre-season maintenance and marketing | Unsecured or cash flow loan, $20,000 to $500,000 | Repaid from peak-season takings |
| Off-season wages and fixed costs | Cash flow loan | Lenders read a full year of statements |
| New tour van, coach or boat | Equipment finance | The vehicle or vessel is the security |
| Lodge refurbishment | 1st or 2nd mortgage, $20,000 to $500,000 | No financials needed, bad credit OK |
| Recovering from a bad season | 2nd mortgage on property | Relies on the property, not last season’s figures |
A second mortgage is often the most practical lever for operators who own their lodge, home or base. It sits behind your bank, leaves your existing 1st mortgage untouched, and doesn’t depend on how the last season traded.
How might a boat cruise operator fund the winter? An illustrative scenario
This is an illustrative example, not a real client.
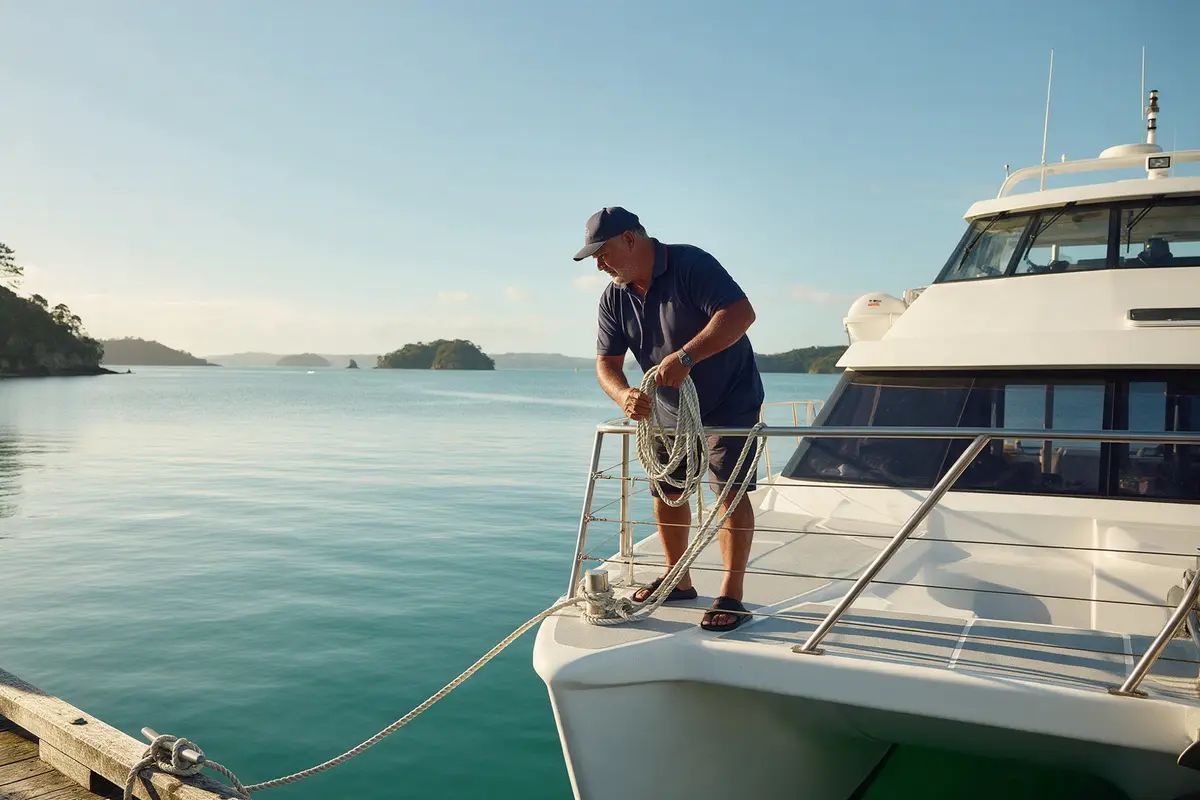
A family-run cruise business in the Bay of Islands runs two vessels out of Paihia. Summer is flat out. Winter is a handful of trips a week.
This year, one vessel is due for its haul-out, survey work and antifouling, and the second needs a pair of replacement outboards. The owners also want to bring their best two crew back early for training. All of it has to happen in winter, when the bank account is at its lowest.
The structure:
- Equipment finance for the new outboards, secured on the engines.
- An unsecured business loan for the haul-out, survey work and early wages, assessed on a full year of bank statements that show a strong summer and a predictable quiet patch.
The loan is sized so repayments sit comfortably inside summer takings. By February, both boats are working full days and the business isn’t scrambling.
If the owners had wanted a larger amount, say to add a third vessel, a 2nd mortgage on their home could have done it without financial statements.
How do you plan loan repayments around the season?
The biggest mistake seasonal operators make is borrowing on a repayment schedule that only works in January. A good structure fits the whole year, quiet months included.
A few practical ways to get it right:
- Size the loan to the trough, not the peak. Work out what you can repay in your quietest month and build from there.
- Match the term to the purpose. Pre-season prep repaid from one summer suits a shorter loan. A new vessel or a lodge refurbishment that earns for years suits a longer term. Our page on short-term business loans explains when a shorter term wins.
- Keep working capital separate from assets. Funding a boat with a cash flow loan, or winter wages with a vehicle loan, makes both harder to manage. A dedicated working capital loan keeps the off-season cleanly funded.
- Plan for tax. GST at 15% on peak-season takings and provisional tax instalments can land when the account is already thin. Put them in the plan.
- Leave headroom. A wet February or a road closure shouldn’t break the budget.
A specialist broker can help you set this up with a lender that understands seasonal businesses, rather than one that only reads your worst month.
What do lenders want to see from a tourism business?
Lenders are comfortable with seasonality when it’s predictable and you can show it. They get nervous when they see a thin peak season, dishonours or a single cancelled contract making up much of the income.
Help your application along:
- Supply 12 months of bank statements so the lender sees both peaks and troughs.
- Bring quotes for the vessel work, vehicle or refurbishment.
- Explain the season plainly: when money comes in and when it goes out.
- Use the business loan calculator to check repayments fit your quiet months, not just your busy ones.
Every loan is priced on your circumstances: security, trading pattern, credit history and the term. LoansOne works to get the sharpest rate available for your situation, and matches you to the right lender instead of shopping your details around.
Next step
Get ahead of the next season instead of chasing it. Apply in about 30 seconds, it’s free and doesn’t mark your credit file. Or call 09-888 5252 and talk to an expert about your operation.