The short answer
Hawke's Bay businesses can get business loans of $20,000 to $500,000 through LoansOne, either unsecured or secured by a 1st or 2nd mortgage over property. Applications from Napier, Hastings and the wider Bay are handled by phone and online, reviewed by an expert, and funding can land in as little as 24 hours.
What is driving business finance in Hawke’s Bay?
Hawke’s Bay runs on things you can see from the Expressway: orchards, vineyards, packhouses, the port and a lot of building sites. A 2024 regional economic report ranked construction as the Bay’s largest employer, followed by horticulture and winemaking, farming and meat processing, and forestry and wood processing. Machinery and equipment manufacturing and food and beverage processing round out the industries the region leans on most.
Much of that construction work is still the long tail of Cyclone Gabrielle. Rebuilding roads, bridges, stopbanks, homes and orchards has kept builders, civil contractors and engineers busy since 2023, and it has stretched their cash flow too. Contractors pay wages and suppliers weekly, while councils and head contractors pay monthly, and sometimes later than that.
Then there is Napier Port, which ships the region’s apples, wine, logs and meat to the world and supports a cluster of freight, cool storage and logistics firms around it.
For a lender, that mix tells a clear story. Hawke’s Bay income is real, but it is lumpy. The best finance here is structured around the season, not against it.
Napier, Hastings and the places in between
The two cities sit side by side, but local businesses borrow for different reasons depending on where and what they trade.
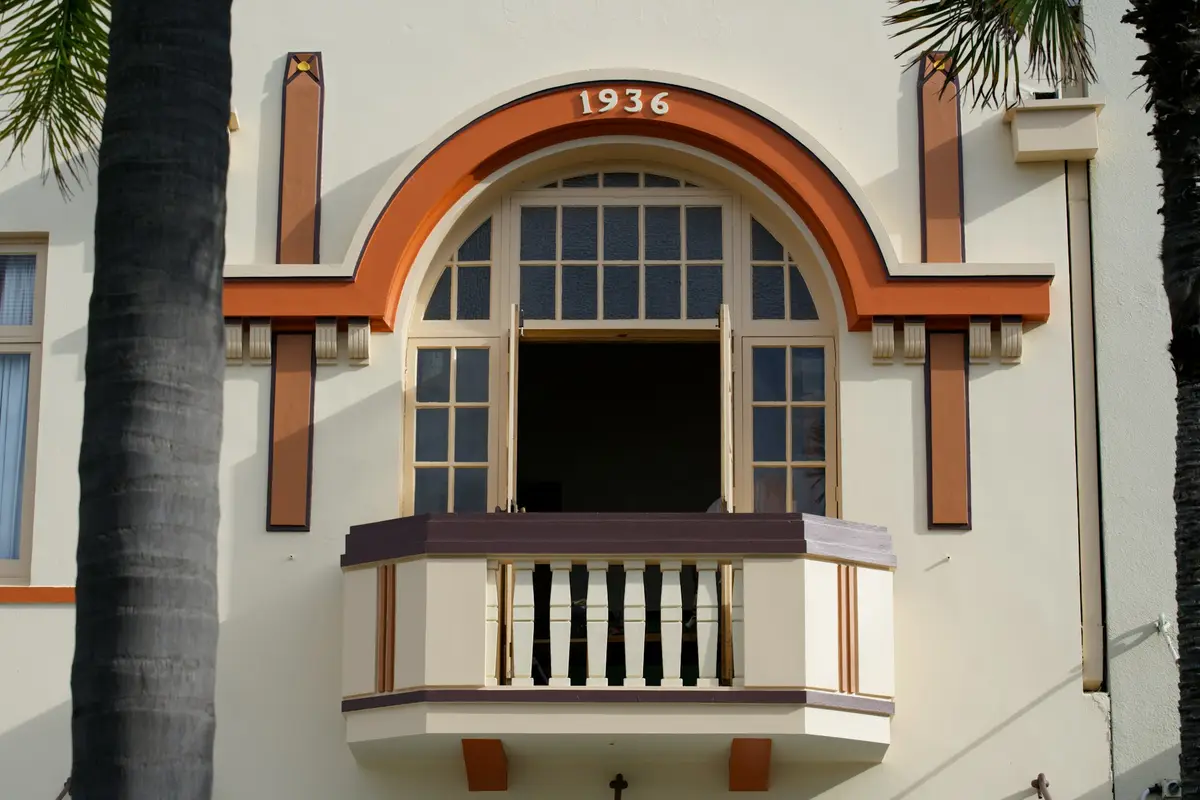
- Napier: Ahuriri’s hospitality and marine businesses, Onekawa and Pandora’s engineering, trade and distribution firms, and the Art Deco CBD’s retailers and tourism operators.
- Hastings: the Omahu Road and Irongate industrial areas with packhouses, cool stores, transport yards and food processors, plus Whakatū’s processing and industrial sites.
- Havelock North: professional services, boutique retail and cafés, and plenty of owners with solid equity in their homes.
- Central Hawke’s Bay and Wairoa: sheep, beef, cropping and the rural contractors who service them.
Whichever part of the Bay you trade from, lenders ask the same three questions: is the business trading, what can it offer as security, and how quickly does it need the money?
How does the harvest calendar affect cash flow in Hawke’s Bay?
If you grow, pick, pack, cart or service fruit and grapes, your year has a shape. Costs land months before income does.
| Time of year | What’s happening in the Bay | Typical funding pressure |
|---|---|---|
| Winter (June to August) | Pruning, orchard redevelopment, vineyard maintenance | Labour and replanting costs with little coming in |
| Spring (September to November) | Flowering, thinning, frost protection, lambing | Frost fans, sprays, fuel and machinery repairs |
| Summer (December to February) | Early fruit, events season, visitor peak | Hospitality staff, stock, extra vehicles |
| Autumn (February to May) | Apple and pear harvest, grape vintage | Picking crews, bins, forklifts and packhouse wages before grower payments arrive |
The squeeze usually comes in late summer. You are hiring, buying and running hard, but grower returns and contract payments may not arrive for weeks or months. A working capital loan sized to cover that gap, then repaid as payments arrive, is often cheaper in practice than juggling an overdraft and late supplier accounts. Our guide to seasonal cash flow goes deeper on matching repayments to your income curve.
Can you use Hawke’s Bay property as security after Gabrielle?
In most cases, yes. Property in Napier, Taradale, Havelock North and the Hastings suburbs is still one of the strongest forms of security a business owner can offer, and lenders treat it that way.
What has changed since 2023 is the level of questioning. Lenders check the title through LINZ, then ask about flood exposure, repairs and insurance. A home or commercial building that was repaired and is fully insured is usually straightforward. A property in a badly affected area may need more explanation, or a different property may make a better security.
There are two ways to use that equity:
- A second mortgage sits behind your existing bank loan, so your bank mortgage stays exactly as it is.
- A private first mortgage replaces or sits in place of bank lending when the bank is too slow or has said no.
Both are available from $20,000 to $500,000 for business purposes, and neither needs cash flow figures or financial records. Bad credit is OK. Run your numbers through the equity calculator to see roughly how much room you have.
An example: a Hastings orchard services contractor
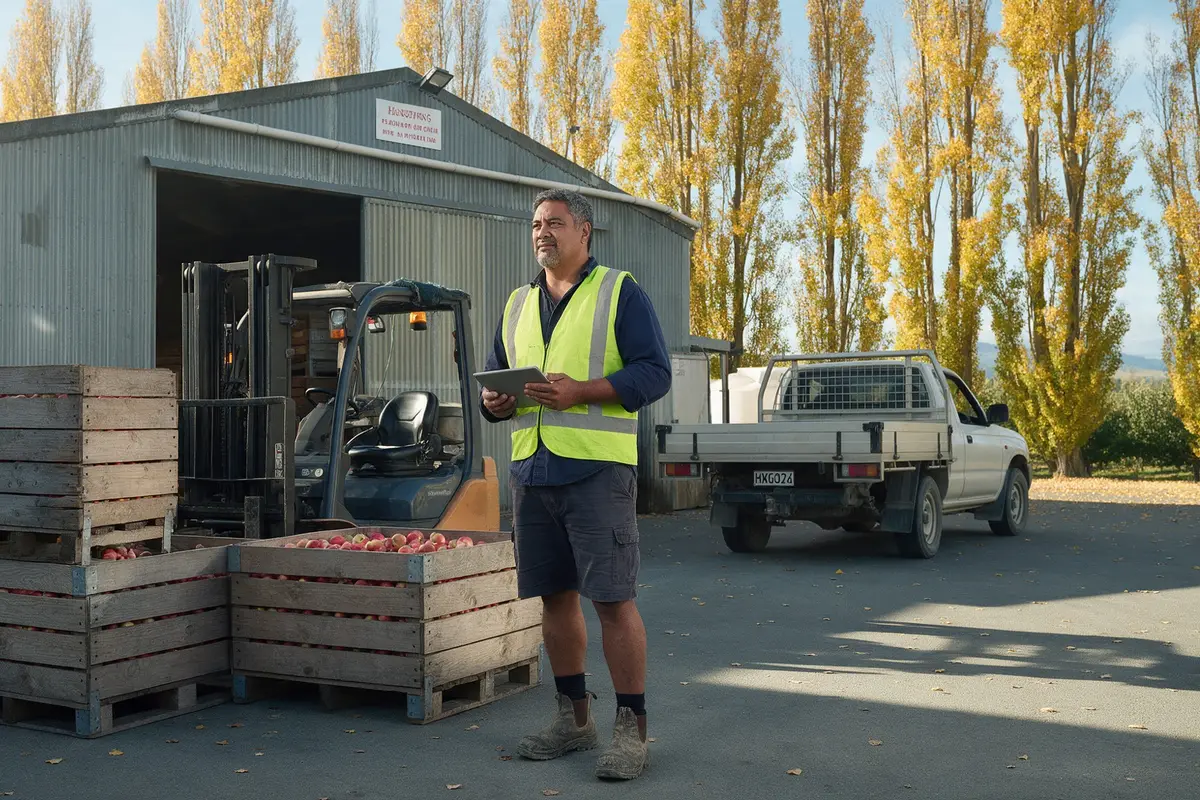
Picture an orchard services business based near Hastings. It supplies picking crews, bin cartage and winter pruning to growers around Twyford and Bridge Pā. Six weeks before harvest, the owner needs $160,000 for two forklifts, a second truck and a month of wages before the first grower invoices are paid.
The bank wants two years of accounts and a few weeks to decide. That doesn’t work when crews start on a fixed date.
Two realistic routes:
- Unsecured loan based on 12 months of business bank statements, if the trading history comfortably supports repayments.
- Second mortgage over the family home in Havelock North, leaving the bank’s first mortgage untouched. No financial records needed, and it can move quickly once the title checks are done.
For the machinery itself, heavy equipment finance could also be part of the mix. This is an illustrative scenario, not a real client, and the right structure always depends on the full picture.
Does LoansOne have an office in Hawke’s Bay?
No. Our office is at 48 Shortland Street in Auckland, and we serve Hawke’s Bay, along with the rest of New Zealand, by phone and online. For most owners that is quicker anyway: no appointment, no time off the orchard or out of the kitchen.
Your application is reviewed by an expert who understands the Bay’s seasonal trade, then matched to one lender that suits your situation. Your details are not sprayed across dozens of finance companies, and starting an enquiry does not mark your credit file. Every loan is priced on your individual circumstances, and we work to get you the sharpest rate available for your situation.
Next step
If harvest, a rebuild contract or a new opportunity is coming up, sort the funding before it bites. Apply in about 30 seconds or call 09-888 5252 to talk it through with the team.