The short answer
Retail business finance in NZ helps shops pay for stock ahead of peak trading, upgrade fit-outs and cover quieter months. LoansOne arranges unsecured loans from $20,000 to $500,000 assessed on your sales, and 1st or 2nd mortgages from $20,000 to $500,000 for larger projects, with bad credit considered on property-backed loans.
Why do retailers need finance at the busiest time of year?
Retail cash flow runs backwards. You pay for stock months before Christmas, then the money arrives in a rush in December. If the order is too small you lose sales; if it’s too big you’re carrying stock into a quiet January with GST due on everything you sold.
The real cash pressures for Kiwi retailers:
- Pre-season buying: suppliers, especially overseas ones, want paying well before the goods sell.
- Peak trading periods: Black Friday, Christmas, Boxing Day, back-to-school and Mother’s Day all need stock and staff in place first.
- The post-Christmas slump: January and February can be quiet in many centres while rent, wages and the GST return keep coming.
- Restricted trading days: most shops must close on Christmas Day, Good Friday, Easter Sunday (unless your council allows it) and Anzac Day morning, which bites in busy weeks.
- Rent reviews and fit-outs: a lease renewal can trigger a costly refit.
- Stock that doesn’t move: cash sits on shelves until it’s cleared.
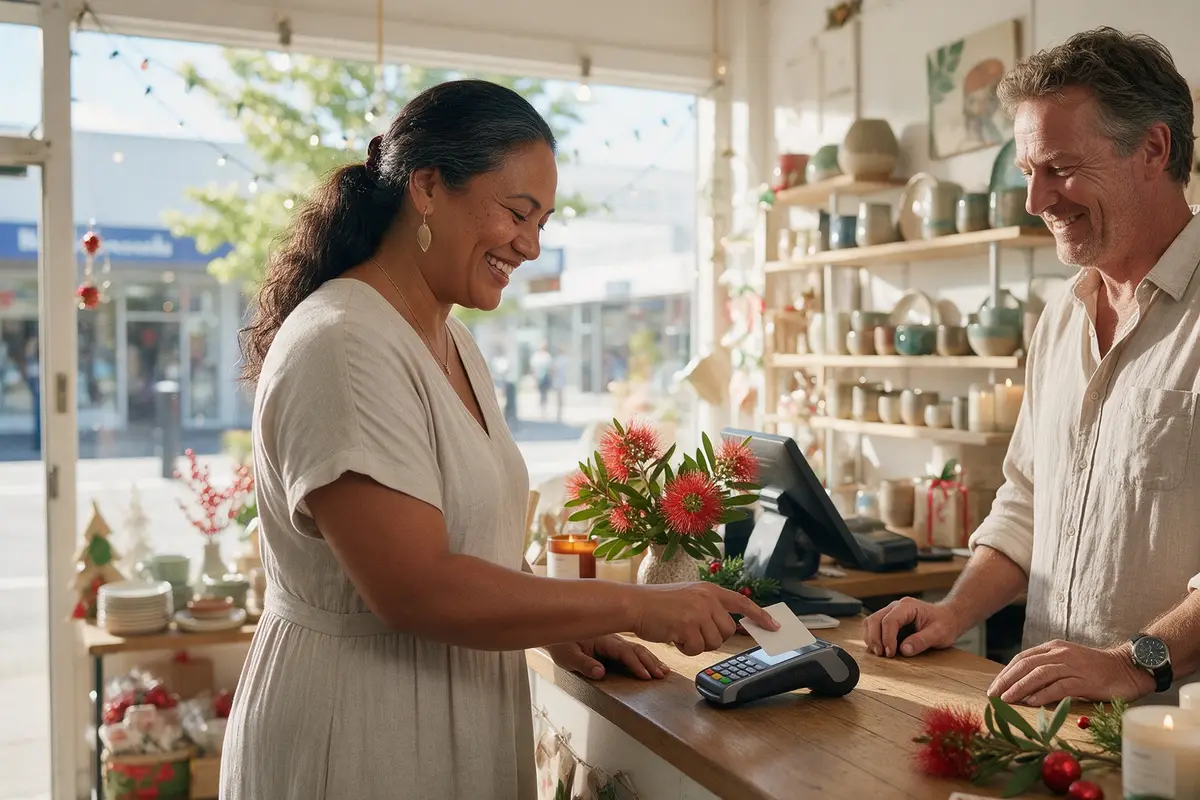
What do retail owners typically fund?
- Seasonal stock orders and bulk-buy supplier discounts
- Shop fit-outs, refits and signage
- A second store, pop-up or larger premises
- Point-of-sale systems, displays and security
- Building an online channel alongside the store
- Covering a GST or provisional tax bill after a strong season
- Buying an existing shop or franchise
Which LoansOne options fit a retail business?
| Need | Option | Why it fits |
|---|---|---|
| Christmas or seasonal stock | Working capital loan | Repaid from the peak-season sales |
| Ongoing stock top-ups | Line of credit | Draw, repay and redraw as orders land |
| Paying overseas suppliers | Trade finance | Pays the supplier before you sell |
| Fit-out or refit | Unsecured business loan | No property needed, $20,000 to $500,000 |
| Larger project, credit issues | 2nd mortgage | No cash flow or financial records needed, bad credit OK |
Retail lending is priced on your sales history, the security offered, the term and purpose. Every loan is priced on your circumstances, and LoansOne works to get the sharpest rate available for your situation.
Illustrative example: a Nelson homewares store
This is an illustrative scenario, not a real client.
A Nelson homewares store takes a large share of its annual sales between late November and Christmas, boosted by summer visitors. The owner’s main supplier offers a bulk discount on the Christmas range if the order is paid by the end of August. The bank overdraft won’t stretch that far.
The owner applies online in a lunch break. An expert reviews two years of bank statements showing the strong December pattern, and the shop is matched to a lender offering a short-term working capital loan sized to the order. The stock lands in October, the discount improves the margin, and the loan is repaid from summer trade. The owner also uses the GST calculator to set aside the GST on December sales before the next return.
What do lenders look at for a retail loan?
- Card and cash takings: steady deposits on your business bank statements, including how your peaks compare year on year.
- Gross margin and stock turn: how quickly stock converts back into cash.
- Lease: term remaining, rent and renewal rights.
- Supplier terms: whether you buy on account or pay up front.
- Security and credit: property equity opens up larger amounts and helps if credit isn’t perfect.
The cash flow gap calculator shows how much you need to carry between paying for stock and selling it, so you don’t borrow more than the gap.
How much stock should a retailer finance?
Enough to meet demand you can prove, and no more. A simple way to size a seasonal stock loan:
- Take last year’s sales for the peak period and adjust for any clear change, such as a new line or a competitor closing.
- Work out the cost of the stock needed to hit that figure at your usual margin.
- Subtract what you can fund from cash and supplier credit.
- The gap is your borrowing need. Add a modest buffer for freight and timing.
If the number feels uncomfortable, order in two stages. Commit early to your proven sellers, then top up once you see how the season starts. A line of credit suits this well because you only draw what you use.
What if the bank won’t extend your overdraft?
It’s common for retailers to outgrow their overdraft, or have it cut back after a slow year. Banks often want updated annual accounts and weeks of review. Private lenders tend to work from recent bank statements and can move far faster. If your accounts are behind or your credit has a blemish, a 2nd mortgage over property you own doesn’t need cash flow or financial records. See business overdraft alternatives for the full picture.
When do different kinds of retailers need cash?
Peaks vary more than most people think, so time your funding to your own calendar:
- Gift, homewares and toy stores: stock for Christmas is ordered mid-year and paid for before November.
- Clothing and footwear: two main seasons, with orders placed months ahead of spring and winter ranges.
- Stationery and school uniform suppliers: back-to-school in late January and February is the big month.
- Garden centres and outdoor stores: spring is the rush, with plants and stock bought in late winter.
- Tourist-town retailers: summer visitors drive the year, with long quiet stretches either side.
How can a shop owner borrow smarter?
- Time the loan to the season: borrow in the buying months, repay in the selling months.
- Only fund stock you’re confident will sell. Last year’s sales are your best guide.
- Keep fit-outs on a separate, longer term than stock funding.
- Set aside GST from every sale so the return doesn’t create a second cash crunch.
- If you sell online too, see how ecommerce business loans handle inventory and ad spend.
Next step
Got a supplier deadline, a refit or a slow patch to get through? Apply in about 30 seconds, free and with no mark on your credit file. An expert reviews your application and matches you with the right lender. Prefer a chat? Call 09-888 5252.