The short answer
Salon business loans in NZ fund fit-outs, styling and treatment equipment, lasers, gym gear, stock and new sites for salons, barbers, beauty clinics, gyms and day spas. LoansOne arranges unsecured loans from $20,000 to $500,000 assessed on trading cash flow, and 1st or 2nd mortgages from $20,000 to $500,000. Next-day funding is possible.
What makes cash flow tricky for salons, clinics and gyms?
Beauty and wellness businesses sell appointments and memberships. Income is steady day to day, but the big costs come in lumps and they come before the money does.
A new salon or clinic needs plumbing, ventilation, lighting and joinery before the first client sits down. A gym spends heavily on equipment and flooring before members sign up. And treatment businesses are under constant pressure to offer the latest device, because clients shop around.
The pressure points we see most in New Zealand:
- Fit-out costs. Basins, plumbing, electrical work, acoustic treatment and joinery add up quickly and have little resale value.
- Equipment that dates. Lasers, skin devices, styling chairs and gym machines need replacing or upgrading to stay competitive.
- Staff and commission. Good stylists, therapists and trainers are hard to find and keep, and wages run every week regardless of bookings.
- Seasonal rhythm. Salons fill up before Christmas and events, then quieten in January. Gyms often see a burst of New Year sign-ups and quieter summer attendance.
- Gift vouchers. Pre-Christmas voucher sales bring cash in early, but the service, product and staff time land months later.
- Retail stock. Product ranges tie up cash on the shelves.
None of this means the business is struggling. It means growth costs money before it earns money. A well-structured loan lets you add the room, the device or the site now, and repay it from the extra bookings it creates, instead of saving for two years while a competitor down the road moves first.
What do beauty and wellness businesses typically fund?
Fit-outs and refurbishments. A new salon, an extra treatment room, a day spa upgrade or a full rebrand of the space.
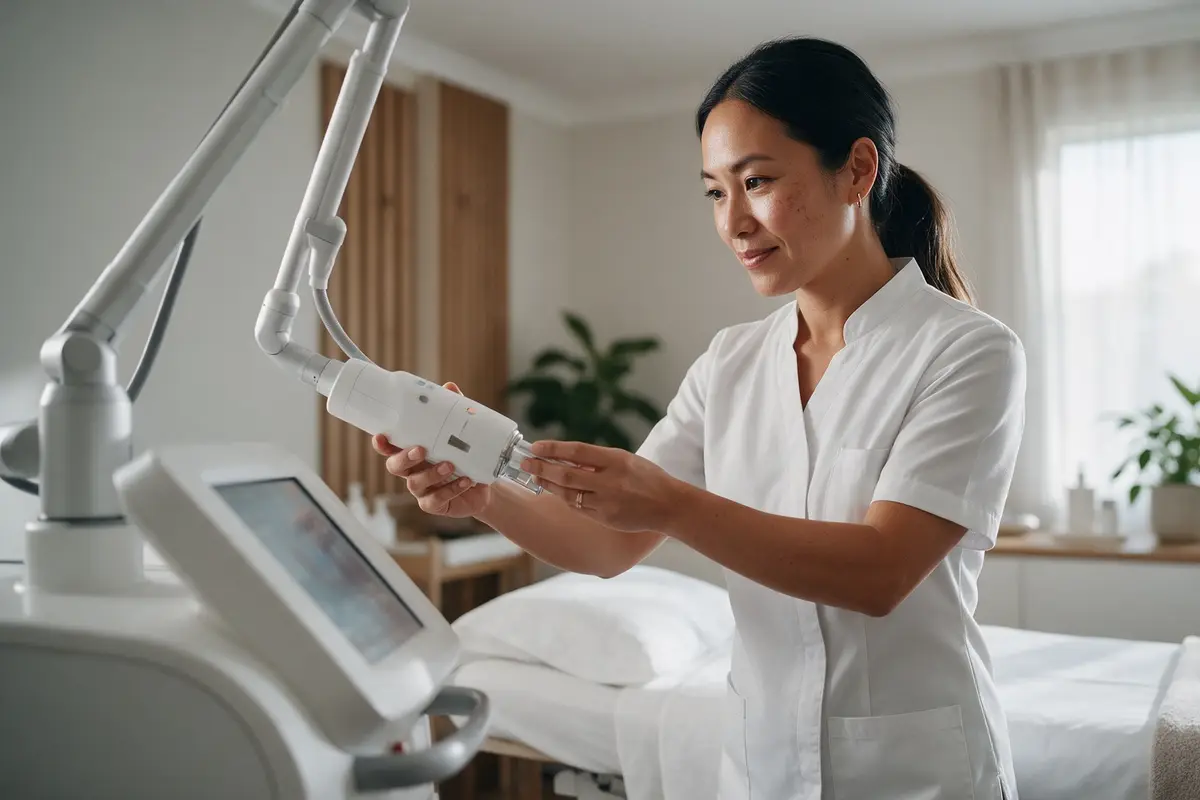
Equipment. Lasers, IPL and skin machines, massage beds, styling chairs, backwash units, sterilisation gear, strength racks, cardio machines and rubber flooring. Much of this suits equipment finance, with the item as security.
A second site. Lease set-up, fit-out and wages while the new location builds its client base.
Stock and working capital. Retail product, consumables and covering wages through quieter months.
Buying a business. Taking over an established salon, clinic or gym, or buying into a fitness franchise. See franchise loans if that’s your path.
Most operators here are small businesses, so our guide to small business loans is a useful companion.
Which LoansOne options fit a beauty or wellness business?
| Business | Typical need | Usually fits |
|---|---|---|
| Hair salon or barber | Fit-out, chairs, basins, signage | Unsecured loan, $20,000 to $500,000 |
| Beauty or skin clinic | Laser or skin device | Equipment finance, plus unsecured loan for room build |
| Day spa | Refurbishment, treatment rooms | Unsecured loan or 1st/2nd mortgage |
| Gym or studio | Equipment, flooring, second site | Equipment finance plus unsecured loan |
| Any, with credit history issues | Any business purpose | 1st or 2nd mortgage, $20,000 to $500,000; bad credit OK |
If you’re a sole operator, our page on sole trader loans covers what lenders look for when the business is you.
Some card-heavy businesses look at an advance repaid from EFTPOS takings. Read our merchant cash advance guide before you go that way, so you can compare it fairly with a standard term loan.
How might a skin clinic fund its next step? An illustrative scenario
This is an illustrative example, not a real client.
A skin clinic in Nelson has built a loyal client base over four years. Its laser treatments are booked out weeks ahead, and the owner is turning people away. She wants to add a second treatment room and a newer laser, and bring on another qualified therapist.
The plan splits in two:
- Equipment finance for the new laser, with the device as security.
- An unsecured business loan for the room build, electrical work, furniture and the new therapist’s first months of wages, assessed on steady card and bank deposits over the past year.
The new room starts taking bookings within weeks, and the extra treatments cover the repayments. If the owner had preferred one simple facility, a 2nd mortgage on her home could have covered everything without financial statements.
Not sure which structure fits your plans? The loan matcher is a quick way to see your likely options.
Is it easier to buy an existing salon or start a new one?
For finance, buying an established business is usually the easier path. A salon, clinic or gym that already trades has a client list, bookings, card takings and equipment that a lender can assess. A brand-new business has a plan and a lease, which is a harder case to lend on unsecured.
| Buying an existing business | Starting from scratch | |
|---|---|---|
| What the lender sees | Trading history and assets | A plan and quotes |
| Unsecured options | Often available | Limited until you trade |
| Common funding route | Unsecured loan or 2nd mortgage | 1st or 2nd mortgage, plus equipment finance |
| Speed to income | Clients from day one | Builds over months |
If you’re looking at a takeover, our page on business acquisition finance covers how purchases are usually funded. If you’re starting fresh, the startup business loans guide is an honest look at what lenders will fund for a new venture.
Either way, check the lease terms, the equipment’s age and whether key staff are staying before you commit. Those details shape what a lender will offer as much as the price does.
What helps a salon, clinic or gym get approved?
Lenders like repeat clients, regular membership direct debits and consistent card takings. They’re more cautious with very new businesses, dishonours, or income that swings wildly week to week.
- Have three to six months of business bank statements ready.
- Get written quotes from your shopfitter or equipment supplier.
- Show how the investment adds capacity: more chairs, rooms or members.
- Mention any IRD arrears up front.
Every loan is priced on your circumstances: security, trading history, credit history and the term. LoansOne works to get the sharpest rate available for your situation, and matches you to the right lender instead of sending your details all over town.
Next step
Ready to fit out, upgrade or open that second site? Apply in about 30 seconds. It’s free and doesn’t mark your credit file. Or call 09-888 5252 to talk it through with an expert.